2.4 C
Berlin
Friday, November 13, 2026
spot_img
Home Blog Page 2

While the US Explores Brain–Computer Interfaces, China Is Already Bringing Them to Patients

0

Brain–computer interface (BCI) technology establishes a direct communication pathway between the brain and external devices by recording and decoding neural activity. Its core function is to translate neural signals into executable commands and use feedback mechanisms to enable closed-loop control. 

Based on signal acquisition methods, BCI systems are generally classified into non-invasive, invasive, and interventional approaches. Non-invasive systems typically collect signals through scalp electroencephalography (EEG), offering relatively convenient use and lower procedural risk, although signal quality can be affected by noise and attenuation. 

Invasive systems use implanted electrodes to obtain higher-quality neural signals, making them promising for precise motor control but raising challenges related to surgical risk and long-term stability. Interventional systems seek to deliver electrodes through vascular pathways, aiming to balance signal quality with reduced surgical trauma. 

BCIs can also be classified by their intended function: restorative systems seek to recover or replace impaired sensory, motor, or communication functions, whereas augmentative systems aim to enhance perception, cognition, or motor performance in healthy individuals. At present, medical treatment and rehabilitation represent the most clearly defined areas of demand and the most promising pathways for clinical translation.

Demand for BCI technology is driven primarily by neurological conditions and injuries that impair movement, sensation, and communication, including spinal cord injury, stroke, Parkinson’s disease, and epilepsy. Conventional medication and rehabilitation can improve patients’ conditions, but restoring voluntary movement and fine motor control remains difficult for people with severe damage to neural pathways. 

By decoding a patient’s movement intentions and translating them into commands for external devices or rehabilitation systems, BCIs offer new possibilities for functional compensation and neurological rehabilitation. However, the commercial potential of these technologies depends not only on technical performance but also on demonstrable clinical benefits, integration into established healthcare pathways, and sustainable reimbursement arrangements. Clinical effectiveness, safety, and affordability are therefore as important as laboratory performance or the number of companies entering the market.

China’s BCI sector is gradually moving from exploratory research toward clinical validation and medical device registration. In March 2026, a brain-controlled hand motor function compensation system developed by Borui Kang received registration approval from China’s National Medical Products Administration (NMPA). Media reports described it as the world’s first approved invasive BCI medical device. The system uses epidural electrodes positioned outside the dura mater rather than directly contacting brain tissue and is designed to compensate for impaired hand movement associated with spinal cord injury. 

According to reports, the product underwent a multicenter confirmatory clinical trial involving 11 hospitals and 32 patients with cervical spinal cord injuries, with some patients reportedly regaining the ability to perform brain-controlled grasping movements. This development marks an important step in China’s transition from technological research to the regulated clinical application of BCI systems for a specific medical indication. Nevertheless, clinical outcomes must be interpreted in the context of trial design, patient selection, follow-up duration, and long-term safety. Results from a defined patient group should not be assumed to apply equally to all people with spinal cord injuries.

Research and development continue across multiple technological approaches. The “Beinao-1” system, developed by Chinese research teams, has been reported to use a wireless, semi-invasive architecture with more than 100 channels, with seven human implantation cases reported. Its successor, “Beinao-2,” entered clinical validation in 2026, reflecting continued efforts to improve high-throughput neural signal acquisition and restore motor or speech functions. 

Non-invasive systems are also being developed for rehabilitation, neurological assessment, and selected mental health applications. Each approach has different technical maturity levels and clinical applications. Invasive systems prioritize high-quality signals and precise control, while non-invasive systems offer advantages in accessibility and lower procedural risk. Interventional systems require further validation of their safety and signal performance. Future competition will depend less on maximizing channel counts or system complexity than on delivering reliable solutions for clearly defined clinical needs.

Policy support has become a major driver of BCI research and industrial development in China. BCI technology has emerged as an important component of national discussions on future industries and scientific innovation, while local governments are using industrial plans, research platforms, clinical infrastructure, and funding mechanisms to accelerate commercialization. In 2026, Guangdong Province issued its Action Plan for the Coordinated Development of Brain-Computer Interface Science, Technology and Industry (2026–2030). 

The plan emphasizes breakthroughs in core technologies, the development of innovation platforms, support for enterprises and products, the expansion of application scenarios, and the improvement of the industrial ecosystem. By 2027, Guangdong aims to achieve technological breakthroughs in more than five major brain diseases, cultivate more than ten core BCI companies, and establish the foundations of industrial clusters in Guangzhou and Shenzhen. By 2030, it plans to add 100 BCI technology companies, promote more than ten non-invasive products with significant market impact, advance several invasive products through clinical translation and medical device registration, and develop 100 demonstration applications. The plan also sets targets of a core BCI industry worth RMB 100 billion and related upstream and downstream industries worth RMB 1 trillion. In addition, it proposes establishing 200 BCI clinical wards and cumulatively serving more than 500,000 patients. These targets demonstrate that policy support extends beyond research funding to clinical infrastructure, regulatory approval, demonstration projects, and industrial chain development. Their achievement, however, will depend on technological maturity, regulatory progress, genuine market demand, and commercially sustainable business models.

Guangdong’s existing industrial base provides a foundation for these policy ambitions. According to a relevant industry white paper, the province has more than 100 key companies with BCI products or products under development, placing it among China’s leading regions in this field. During the reporting period, Guangdong recorded 27 registered BCI clinical trials, accounting for 20.1% of the national total. Twenty-eight medical institutions had established or planned to establish BCI clinical research wards, while the province recorded 360 BCI patent applications. These figures indicate that Guangdong’s strengths extend beyond corporate concentration to clinical research capacity and intellectual property development. Guangzhou and Shenzhen form the province’s principal industrial centers, while other cities in the Pearl River Delta can contribute supporting capabilities in electronics, artificial intelligence, precision manufacturing, and healthcare. The key policy challenge is to translate the number of companies and patents into competitive core components, clinically validated products, and replicable application models.

Shanghai and Wuhan illustrate different but complementary regional development pathways. According to reports published in 2026, Shanghai’s Minhang District had attracted 61 BCI-related companies, including 13 focused on invasive technologies, 36 on non-invasive technologies, and 12 on supporting services. The cluster had accumulated more than RMB 1 billion in financing, while the combined valuation of its core companies exceeded RMB 5.5 billion. 

Eight BCI products had reached the clinical stage, and the development pipeline contained more than 50 products or programs. The local ecosystem also includes proof-of-concept platforms, clinical research wards, data infrastructure, and industrial investment funds. A related EEG data platform was reported to contain more than 100,000 cases, providing resources for algorithm development and clinical research. Shanghai’s advantages lie in the integration of capital, research, medical resources, and medical device development. However, company valuations and pipeline size are not substitutes for regulatory approval or demonstrated commercial performance.

Wuhan, by contrast, has developed distinctive strengths in clinical resources and collaboration between engineering and medicine. Reports indicate that hospitals across the city have conducted clinical explorations involving invasive, semi-invasive, and non-invasive BCI systems. Clinical trials at institutions including Tongji Hospital and Union Hospital have exceeded 60, with more than 60% reportedly commissioned by companies based outside Hubei Province. Union Hospital’s engineering–medicine integrated ward has provided related services to more than 200 patients with spinal cord injuries, stroke, Parkinson’s disease, and epilepsy. 

These figures highlight Wuhan’s capacity to support clinical research and suggest that hospitals serve not only as end users but also as essential partners in technology validation, indication development, and product improvement. Compared with Guangdong’s manufacturing and corporate concentration and Shanghai’s capital and commercialization resources, Wuhan’s clinical infrastructure provides a strong basis for testing technologies against real medical needs. Cooperation among these regions could help connect research, clinical validation, manufacturing, and commercialization.

Despite these advances, the further development of BCI technology faces significant technical, regulatory, and industrial challenges. Individual differences in neural signals, decoding accuracy in complex environments, long-term electrode stability, device maintenance, and infection risks all require continued investigation and clinical follow-up. Neural data are highly sensitive and raise concerns about personal privacy, data security, and informed consent. Clear rules are therefore needed for data collection, use, storage, and sharing. Because BCI development spans neuroscience, clinical medicine, materials science, microelectronics, artificial intelligence, and precision manufacturing, few companies can independently manage the entire process from fundamental research to commercial deployment. Public testing platforms, animal research facilities, clinical research wards, technical standards, and technology transfer services are consequently essential components of the industrial ecosystem. Policy support should encourage innovation while strengthening requirements for clinical evidence, ethical review, product quality, and long-term safety, preventing preliminary trial results from being misinterpreted as established and universally applicable treatment outcomes.

Source: stdaily, jiangmen gov cn, gdppnet, most gov cn, jingji cctv, wuhan gov cn, tmtpost
China Is the World’s Largest Electricity Producer and Consumer. Now, Even Its Highways Are Generating Power

0

China is beginning to use its highways to generate electricity. In the past, highways were built primarily to improve transportation efficiency and support economic development. Once completed, their main sources of operating revenue were tolls, service areas, and related businesses. 

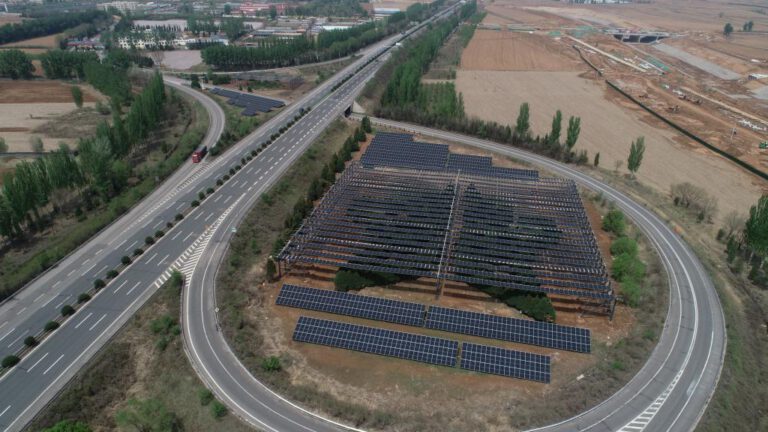
Today, however, this business model is evolving. Highways are no longer just transportation infrastructure. They are increasingly becoming platforms for energy generation, storage, and electricity trading. Solar panels are appearing along roadside slopes, service-area rooftops, toll stations, and parking shelters, while charging stations, energy storage systems, and virtual power plants are becoming part of highway operations. China is turning its existing transportation infrastructure into an asset capable of generating additional energy revenue.

This transformation goes beyond simply installing solar panels beside roads. It represents a second phase in the development of existing infrastructure. China has nearly 200,000 kilometers of expressways, with extensive areas along these routes occupied by slopes, interchanges, service areas, and toll stations. 

Although these spaces were created as part of highway construction, not all of them are directly used for vehicle movement. In the past, they primarily served functions such as road protection, parking, and passenger services. Today, suitable areas can also be used to generate electricity, allowing infrastructure originally designed for transportation to take on an additional role in energy production.

Early solar highway experiments in Jinan, Shandong Province, demonstrated the potential of combining road transportation with solar power generation. The experimental section incorporated photovoltaic technology into the road surface itself. However, large-scale deployment does not necessarily require covering every road with solar panels. 

Considering construction costs, load-bearing requirements, maintenance difficulties, and power generation efficiency, service-area rooftops, parking shelters, and suitable roadside slopes are often more practical locations for expansion. The real objective is not to turn every square meter of pavement into a solar panel, but to make underutilized spaces along highways generate additional economic value without compromising road safety or normal operations.

Another major reason highway operators are expanding into renewable energy is the pressure on traditional business models. Expressway construction requires substantial capital investment and typically has a long payback period. Operators must also continue spending on maintenance, upgrades, and daily operations. 

Toll revenue remains important, but it is affected by traffic volumes, toll policies, concession periods, and changes in the road network. Relying exclusively on tolls makes it difficult to secure long-term growth. Highway operators therefore need new sources of income, and the land, buildings, vehicle traffic, and existing electrical infrastructure along their routes provide a foundation for developing energy businesses.

Solar power can generate electricity sales revenue while reducing a highway operator’s own energy costs. Service areas, toll stations, tunnels, lighting systems, and monitoring equipment all consume electricity. If solar installations can meet part of this demand, operators can reduce their purchases from the grid. Surplus electricity can potentially be fed into the grid or sold through electricity markets, depending on the project’s configuration and local regulations. 

Meanwhile, the growing number of electric vehicles is increasing demand for charging services at highway service areas. Charging infrastructure has consequently become another source of business opportunities. Through direct operation, partnerships, or site leasing, highway companies can earn charging revenue, rental income, or a share of operating profits while continuing to provide transportation services.

The significance of this model lies in its ability to create additional value without necessarily requiring an entirely new infrastructure network. It builds on existing roads, land, facilities, and operating systems. For highway companies that have already invested heavily in construction, energy services provide an additional revenue stream from existing assets. 

Solar panels, storage systems, and charging facilities still require upfront investment and ongoing maintenance, and their economics depend on grid connections, electricity prices, and market conditions. Their revenue should not simply be treated as pure profit. Nevertheless, when projects are appropriately located and investment costs remain manageable, energy businesses can improve asset utilization and strengthen the long-term financial performance of highway operations.

A deeper reason behind this development is China’s growing demand for electricity. In the past, power consumption was driven mainly by industrial production, households, and traditional commercial activities. Today, the expansion of electric vehicles, manufacturing upgrades, data centers, and artificial intelligence is creating additional demand. Electricity is no longer simply a basic necessity for daily life. 

It increasingly determines industrial capacity, the development of the digital economy, and national competitiveness. For a country with a vast manufacturing sector and an ongoing industrial transformation, energy planning cannot focus solely on whether current demand can be met. It must also prepare for future factories, computing centers, and the electrification of transportation.

This explains why highways are becoming more valuable as energy assets. China’s road network is a widely distributed infrastructure system with extensive land resources, established electricity-consuming facilities, and growing vehicle traffic. As electric vehicles become more common, highway service areas are evolving from simple rest stops into important energy supply hubs. 

The greater the demand for charging, the more important reliable electricity supplies become. By combining solar generation with energy storage, some service areas can develop integrated systems that generate, store, and supply electricity. These systems can help manage concentrated charging demand and increase the local use of renewable energy.

The virtual power plant project developed by Hubei Communications Investment New Energy Company illustrates the direction this business could take. In June 2026, the project completed registration and public announcement through the Hubei Power Trading Center, obtaining the qualifications required to participate in market-based electricity trading. The company installed and commissioned specialized metering equipment and frequency-regulation gateways at high-power charging stations across the Xiaogan, Jianghan, and Enshi areas. The system achieved an adjustable capacity of 13.79 megawatts. According to the company’s estimates, participation in multiple electricity market services could generate more than RMB 2 million in annual combined revenue, with a static investment payback period of no more than six years.

A virtual power plant is not a conventional power station. Instead, it uses a digital platform to integrate distributed resources, including solar installations, energy storage systems, and charging stations across multiple service areas. These resources can then be monitored and dispatched as a coordinated system, enabling them to participate in electricity markets. For example, electricity can be stored when prices are low and released during periods of peak demand. When the power grid is under pressure, charging equipment can also adjust its consumption. This creates new opportunities to earn revenue from electricity trading and grid-support services. Equipment that once served only as a source of electricity demand can now help balance the power system.

This means competition in the highway energy business may eventually depend on more than the number of solar panels installed or charging points built. The ability to integrate generation, storage, charging, and electricity trading could become equally important. A standalone solar project generally depends on its output and the price of electricity. By improving self-consumption, shifting electricity use between different periods, deploying storage, and participating in market-based services through virtual power plants, operators may unlock additional value from the same energy resources. However, this approach still faces challenges involving technical integration, specialized talent, electricity market rules, and the distribution of returns among different parties. Actual results will depend on local policies, project conditions, and market mechanisms. The financial performance of one project cannot automatically be replicated across every highway.

At a broader level, the expansion of renewable energy along highways represents an extension of China’s infrastructure development strategy. In the past, infrastructure investment primarily focused on building the networks needed for transportation, water management, communications, and energy supply. The priority was to create the physical foundations for economic activity. Now, as the country’s existing infrastructure network continues to expand and new investment faces greater pressure to deliver economic returns, making existing assets serve multiple purposes is becoming increasingly important.

Highways can generate electricity, service areas can store and supply power, charging stations can help regulate electricity demand, and transportation networks can become integrated with energy networks. Infrastructure is therefore evolving beyond its traditional role as a cost of economic development. It can also become a productive asset and a distributed node in the energy system.

Of course, this does not mean solar installations along highways can solve all of China’s electricity needs. Development is constrained by sunlight, terrain, grid connection capacity, and road safety requirements. Solar generation is also intermittent and cannot replace the need for reliable power sources, grid expansion, and other energy investments. Its real value lies in increasing clean electricity generation by making use of an existing transportation network, potentially reducing the need for additional land while creating new revenue opportunities for highway operators.

As China’s industrial production, digital economy, and transportation systems become increasingly dependent on electricity, power supply will no longer come exclusively from conventional power stations and the grid. Factory rooftops, industrial parks, buildings, and highway corridors can all become components of a distributed energy system.

China’s highways are beginning to generate electricity not merely because transportation companies have discovered a new business opportunity, but because the country is seeking to extract greater economic value from its enormous infrastructure network. Assets once designed primarily to move people and goods are now being developed to support energy generation, supply, and regulation as well.

This is both a shift from single-purpose infrastructure toward integrated resource utilization and a practical attempt to expand electricity supply capacity in preparation for China’s future energy needs.

Source: global net zero, sasac, xinhua, nea gov cn, china daily, sohu

China’s Railway: From Building a Basic Network to Becoming a Global High-Speed Rail Leader

0

In the early years of the People’s Republic of China, the country’s railway system faced a fundamental challenge: restoring transportation services, connecting different regions, and supporting national economic development. Over the past seven decades, China’s railways have evolved from a relatively underdeveloped network with limited capacity into a modern railway system featuring advanced technologies, an extensive operational network, and one of the world’s largest high-speed rail networks. 

Today, China has 165,000 kilometers of operational railway lines, including more than 50,000 kilometers of high-speed rail. Railways have not only transformed the way people travel but have also profoundly influenced China’s industrial development, regional economies, urban growth, and international trade.

The development of China’s railway system has always been closely connected to the country’s national priorities and changing social needs. In the early years after the founding of the People’s Republic of China, the country had just over 20,000 kilometers of operational railway lines. Many existing lines had been damaged by war, and the national railway network remained incomplete. 

At that time, railways played a fundamental role in supporting industrial production and the national economy. Coal, steel, grain, and other essential materials all depended on rail transportation to move across regions. Restoring existing lines and constructing new railway routes therefore became essential tasks in national economic development. 

The completion of major projects, including the Chengdu–Chongqing, Tianshui–Lanzhou, Baoji–Chengdu, Lanzhou–Xinjiang, and Chengdu–Kunming railways, gradually expanded the national railway network. These projects improved regional connectivity while providing vital support for industrial development, resource utilization, and economic growth. China’s participation in the construction of the Tanzania–Zambia Railway also marked an early milestone in its international railway cooperation.

Following the launch of reform and opening-up, China experienced rapid economic growth, accelerating urbanization, and increasing population mobility. Industrial production, urban development, and foreign trade expanded significantly, driving railway demand to unprecedented levels. 

Existing infrastructure struggled to keep pace with this growth, shifting the central challenge from whether railway connections existed to whether the network had sufficient capacity. During this period, China invested heavily in double-track construction, railway electrification, locomotive and rolling stock upgrades, and improvements in transportation management. 

Beginning in 1997, a series of major railway speed increases significantly reduced passenger travel times while improving the overall efficiency of existing lines. Major projects such as the Beijing–Kowloon Railway and the Lanzhou–Xinjiang double-track railway further strengthened the national network, while heavy-haul railways such as the Daqin Railway enhanced freight transportation capacity. 

The Qinghai–Tibet Railway overcame extraordinary engineering challenges, including high-altitude conditions, permafrost, and fragile ecosystems, extending the railway network to the Tibetan Plateau. China’s railway development was therefore shifting from simply expanding the network toward improving speed, capacity, and technological standards.

Entering the 21st century, the growth of urban clusters and increasing interregional travel created new demands on traditional railway transportation. In 2004, China began systematically advancing the development of dedicated passenger rail corridors. The opening of the Beijing–Tianjin Intercity Railway in 2008 marked the beginning of a new era of large-scale high-speed rail construction and operation. 

Subsequently, major high-speed railways, including the Beijing–Shanghai, Wuhan–Guangzhou, and Zhengzhou–Xi’an lines, entered service, extending the high-speed rail network across the country. The Medium- and Long-Term Railway Network Plan released in 2016 further established the framework of eight north–south and eight east–west high-speed rail corridors, providing a long-term blueprint for national network development. By the end of 2025, China’s high-speed rail network had exceeded 50,000 kilometers, connecting major cities and urban clusters across the country.

China’s rapid progress in high-speed rail has not been driven by large-scale investment alone. It is the result of long-term planning, engineering expertise, advanced manufacturing, and sustained technological innovation. Through decades of research, technology transfer, and independent development, China has established a comprehensive technological system covering railway design, track systems, traction power supply, communications and signaling, train control, and high-speed train manufacturing. 

The Beijing–Zhangjiakou High-Speed Railway, for example, incorporates intelligent construction technologies and automatic train operation in a challenging geographical environment. Fuxing high-speed trains continue to improve operational performance and safety, while advances in bridges, tunnels, tunnel-boring machines, and track engineering have strengthened China’s overall railway construction capabilities. 

By addressing challenges ranging from high-altitude permafrost to complex geological conditions, extreme cold, and desert environments, China has accumulated extensive experience in railway engineering and operations. Its railway industry has progressed from technological catch-up to independent innovation and increasingly sophisticated system integration.

The significance of high-speed rail extends far beyond faster trains. By transferring a substantial proportion of long-distance passenger traffic to dedicated high-speed lines, China has also released capacity on conventional railways. These existing lines can continue to serve freight transportation, conventional passenger services, and more affordable travel. 

As a result, China has gradually developed a multi-layered railway system consisting of high-speed railways, conventional railways, intercity railways, suburban railways, and dedicated industrial railway lines. High-speed rail primarily serves long- and medium-distance passenger travel, while intercity railways strengthen connections within urban clusters. Suburban railways increasingly support commuting within metropolitan areas, and conventional railways continue to provide extensive coverage and cost-effective passenger and freight services. Together, these different types of railways form an integrated national transportation network capable of meeting the needs of different regions, industries, and population groups.

The development of China’s railway system is also reflected in the continuous improvement of transportation services and public welfare. The annual Spring Festival travel rush, known as Chunyun, offers a particularly clear illustration of this transformation. In 1954, China’s railways carried approximately 23 million passengers during the Spring Festival travel period. By 2024, the figure was expected to reach 480 million. 

To accommodate this enormous growth in demand, railway services have evolved from adding temporary trains and optimizing scheduling to providing online ticketing, electronic tickets, and increasingly intelligent passenger services. Online ticket sales were first introduced during the 2012 Spring Festival travel rush, and the 12306 ticketing system has continued to develop, fundamentally changing how passengers purchase tickets and plan their journeys. Locomotive technology has also advanced from steam and diesel engines to electric locomotives and Fuxing high-speed trains, greatly improving transportation efficiency and service quality.

At the same time, China’s railway development has not overlooked the basic travel needs of people living in remote and less-developed regions. Public-service local trains continue to operate on mountainous routes, in remote communities, and in areas with limited transportation alternatives. These trains provide essential services for residents traveling to school, seeking medical treatment, attending markets, visiting relatives, and transporting agricultural products. 

For many communities along these routes, the trains are more than just a means of transportation; they are vital links to external markets and public services. The value of railway development therefore lies not only in the efficiency of high-speed trains but also in the continued commitment of conventional services to meeting everyday public needs.

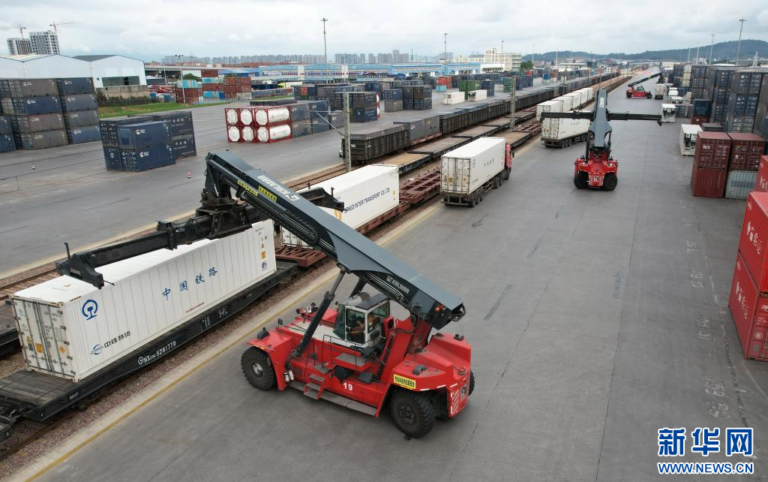
Railway transportation has also expanded into specialized logistics and international markets. Cold-chain transportation is an important example. In 1953, China’s railway authorities officially began transporting perishable goods and started developing refrigerated railway wagons. Over subsequent decades, advances in refrigeration, insulation, ventilation, and transportation management enabled the gradual establishment of a nationwide railway cold-chain network. 

This system has provided reliable transportation for food, agricultural products, and other temperature-sensitive goods. In recent years, with the opening of international routes such as the China–Laos Railway, railway cold-chain services have increasingly extended into cross-border logistics. Through the use of new refrigerated wagons, remote monitoring, and specialized maintenance systems, these services have improved cargo quality control, shortened transportation times, reduced cargo losses, and supported regional trade. Looking ahead, intelligent monitoring, data analytics, energy efficiency, environmental protection, and multimodal transportation will play increasingly important roles in the development of railway cold-chain logistics.

The rapid development of China’s railways has also been supported by continuous institutional reform. In 2013, China implemented a major restructuring of its railway administration, separating the government’s regulatory functions from the railway sector’s business operations. Government responsibilities were transferred to institutions including the Ministry of Transport and the National Railway Administration, while railway business operations were assumed by China State Railway Group. 

This reform established a clearer division of responsibilities: government agencies oversee industry regulation and safety supervision, while China State Railway Group is responsible for the operation and coordination of the national railway system. Meanwhile, China State Railway Group and China Railway Construction Corporation primarily undertake railway engineering and construction, while CRRC Corporation Limited focuses on manufacturing locomotives, passenger trains, and other railway equipment. These organizations perform different but complementary roles in railway construction, equipment manufacturing, and operations.

Separating government administration from business operations does not mean that the railway network can function as a collection of independent systems. Railways are highly interconnected. Every train’s departure time, station stops, route allocation, and passing arrangements must be coordinated with other trains and the wider network. The national train timetable is effectively a comprehensive scheduling system that determines how railway capacity is allocated while ensuring operational safety and efficiency. Therefore, although the 2013 reform separated regulatory responsibilities from commercial operations, the national railway system still requires unified coordination and dispatching to maximize the efficiency of the entire network.

Railway construction is also a capital-intensive undertaking requiring substantial long-term investment. In the past, the main priority was to expand the network and address infrastructure shortages as quickly as possible. As the network has grown, however, investment decisions have increasingly focused on passenger demand, economic returns, and the financial capacity of local governments. Railway projects are commonly financed through the combined participation of China State Railway Group, local governments, and financial institutions. 

Local governments may contribute part of the project’s initial capital, as well as funding for land acquisition, demolition, and supporting infrastructure around railway stations. The remaining funds may be raised through bank loans, bonds, and other financing channels. Once a railway is completed, it must cover interest payments, maintenance, and operating expenses over many years. Project planning must therefore consider not only construction requirements but also future passenger demand, transportation revenue, and long-term debt repayment capacity.

This means that China’s railway development is gradually shifting from an emphasis on expanding construction scale toward improving project quality and investment efficiency. Different regions have different population sizes, industrial foundations, economic conditions, and transportation needs. Not every railway project requires the highest construction standard. High-speed railways designed for 350 kilometers per hour or 250 kilometers per hour, conventional railways, and other regional lines each serve different purposes. Determining the appropriate technical standards, station locations, and construction schedules requires balancing regional development needs with long-term operating costs and local fiscal capacity. The central question is no longer simply whether a railway can be built, but which type of railway is most suitable for a particular region.

The impact of railways on regional economies also requires a balanced perspective. High-speed rail reduces travel time between cities, making business cooperation, tourism, consumption, and access to public services more convenient. It also creates opportunities for industrial relocation and regional integration. 

However, improved transportation does not automatically generate economic growth. After a high-speed railway opens, industries and population may concentrate in cities along the route. At the same time, it may accelerate the movement of talent, consumption, and capital toward larger metropolitan centers. Whether a city ultimately benefits depends on its industrial base, ability to attract residents and businesses, quality of public services, and overall urban governance. Railways can improve the external conditions for urban development, but they cannot replace the need to build strong industries and long-term competitiveness.

As China’s railway network has become increasingly sophisticated, its development has also expanded beyond domestic infrastructure to international markets. The Tanzania–Zambia Railway marked an early stage of China’s overseas railway cooperation. More recent projects, including the China–Laos Railway, the Jakarta–Bandung High-Speed Railway, and the Hungary–Serbia Railway, demonstrate the growing international presence of Chinese railway technology, equipment, and engineering capabilities. 

Chinese railway companies are increasingly participating in overseas projects through design, construction, equipment supply, operation, and maintenance, while exploring comprehensive service models covering the entire railway industry chain. Meanwhile, the China–Europe Railway Express has continued to expand international logistics routes, strengthening trade links between China, Europe, and countries along the corridors. Railways have thus become not only essential infrastructure for China’s domestic economy but also an important means of promoting international connectivity and regional cooperation.

From restoring railway lines and connecting the country in the early years of the People’s Republic of China, to increasing transportation capacity during the reform and opening-up period, and eventually building one of the world’s largest high-speed rail networks, China’s railway development over more than seven decades reflects the continuous improvement of the country’s industrial capabilities, technological innovation, organizational capacity, and overall national strength. 

Railway construction has connected previously isolated regions. Advances in railway technology have driven innovation in high-end equipment manufacturing and engineering. Railway operations have supported large-scale population mobility and freight transportation, while the expanding network has continuously reshaped relationships between cities, industries, and regions.

Today, the challenges facing China’s railway system go beyond speed and mileage. The priorities are increasingly focused on how to improve coordination between different types of railways, balance infrastructure development with investment constraints, enhance transportation efficiency, and ensure that the railway network better serves industrial development and public needs. Looking ahead, China’s railways will continue to advance toward greater intelligence, sustainability, network integration, and international cooperation, playing an increasingly important role in the country’s broader goal of becoming a leading transportation power.

From the question of whether railway connections existed, to whether transportation capacity was sufficient, and now to how to build and operate a more efficient and sustainable railway network, China’s railway development has continually adapted to the changing needs of the country and its people. The railway system is no longer simply a means of transportation. It has become essential infrastructure connecting national strategies, industrial development, urban growth, and everyday life.

Source: china railway, xinhua, csrc, people

Xinjiang: From a Traditional Agricultural and Pastoral Region to a Fertile Ground for China’s Renewable Energy Development

0

Xinjiang has traditionally relied on agriculture and animal husbandry as the main pillars of its economy. Constrained by geographical conditions, transportation infrastructure and a relatively limited industrial base, the region historically experienced slower economic development. Yet its vast Gobi deserts, abundant sunshine, extensive mountain ranges and powerful winds have also given it exceptional potential for renewable energy. 

Xinjiang’s renewable energy development is built not only on its natural resource advantages, but also on decades of industrial exploration. As early as the 1980s, the region began researching, testing and promoting wind power technology. In 1986, Xinjiang introduced its first wind turbine. The first phase of the Dabancheng Wind Farm was completed in 1988, and the facility was connected to the grid in 1989. By 1994, Dabancheng had become home to one of China’s largest commercial wind farms at the time, earning its place as an important birthplace of the country’s wind power industry. 

From initially importing turbines from Denmark and other countries, to gradually localizing the production of key components such as towers, blades, gearboxes and control systems, and eventually developing independently designed direct-drive permanent-magnet turbines, Dabancheng has witnessed China’s wind power industry evolve from technology importation and domestic substitution to international competitiveness. This region, once primarily known for farming and animal husbandry, began exploring a new path from traditional resource use to a modern energy industry.

Over the past three decades, wind power development in Xinjiang has continued to advance towards larger-scale projects, greater efficiency and more sophisticated technology. The Dabancheng Wind Farm has been upgrading its older turbines, replacing early-generation equipment with larger and more advanced models to improve the utilization of wind resources. 

Technologies such as LiDAR-based wind measurement enable turbines to detect wind speed and direction more accurately, helping increase power generation efficiency and reduce operation and maintenance costs. Meanwhile, the wind power industry chain continues to expand, bringing together turbine manufacturing, engineering construction, equipment maintenance and technological research. 

Renewable energy is no longer simply a collection of turbines installed across open landscapes. It has become an important driver of local industrial development, employment and technological progress. In places such as Mulei, wind power equipment manufacturers are expanding their production capacity, providing essential support for the regional renewable energy industry while creating new employment opportunities for local communities.

If wind power represents the historical foundation of Xinjiang’s renewable energy development, the rapid rise of solar power has further unlocked the region’s enormous natural potential. With abundant sunshine and extensive Gobi and desert landscapes, Xinjiang is ideally suited for large-scale photovoltaic power generation. 

In recent years, major renewable energy bases in Hami, Zhundong and the southern Xinjiang region surrounding the Tarim Basin have accelerated their development. Solar projects are spreading across deserts and Gobi landscapes, gradually forming large-scale, integrated development zones. 

In places such as Ruoqiang, photovoltaic projects with capacities of one million kilowatts and beyond have been built and brought into operation, turning land that was previously unsuitable for conventional agricultural production into space for generating clean electricity. Meanwhile, the Tarim Oilfield has developed large-scale solar power stations in areas including Bazhou and Kashgar. In Luopu County, Hotan, initiatives such as combining photovoltaic power generation with agriculture and desertification control are exploring ways to integrate clean energy production, land utilization and ecological restoration.

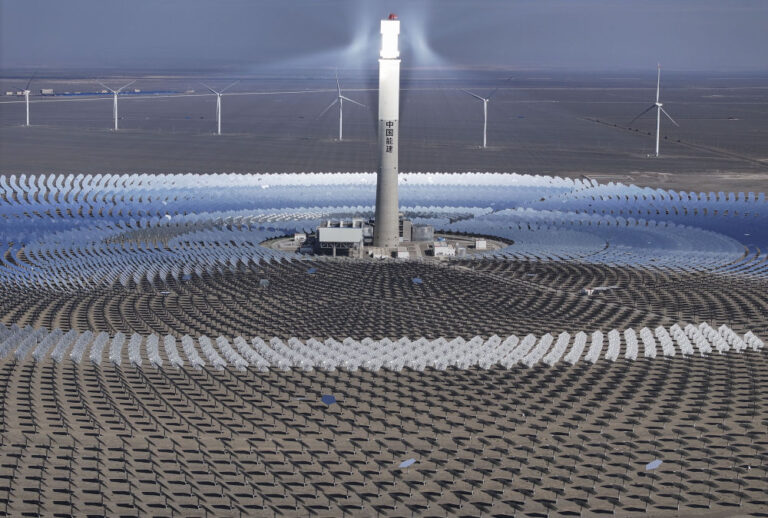
The coordinated development of wind and solar power is reshaping Xinjiang’s energy landscape. In recent years, the region’s installed renewable energy capacity has grown rapidly, transforming it from an important traditional energy-producing area into one of China’s major renewable energy development hubs. 

By the end of February 2026, Xinjiang’s installed renewable energy capacity had exceeded 173 million kilowatts, accounting for more than 60 percent of its total installed power generation capacity. Several renewable energy bases, each with a capacity of over 10 million kilowatts, have taken shape. In 2025, renewable energy generation in Xinjiang reached 146.7 billion kilowatt-hours, representing a year-on-year increase of 22.3 percent. 

The value of renewable energy extends far beyond generating more electricity. Located in northwestern China, Xinjiang has abundant wind and solar resources, but the scale of local electricity consumption does not always match the rapid expansion of energy production. One of the key challenges is therefore how to transmit the green electricity generated across its deserts and Gobi landscapes to wider markets. 

In recent years, Xinjiang has continued to strengthen its power grid, developing a transmission network supported by a 750-kilovolt backbone grid. Ultra-high-voltage direct-current transmission projects are connecting energy resources in western China with major electricity-consuming regions in the central and eastern parts of the country. 

Since the launch of the Xinjiang electricity transmission in 2010, electricity generated in the region has been delivered to numerous provinces, with renewable energy accounting for an increasingly significant share of the exported power. The Xinjiang-to-Chongqing transmission project, which entered operation in 2025, has further expanded the region’s capacity to deliver clean energy beyond its borders. Wind and solar power generated in the deserts of northwestern China can now travel thousands of kilometres to support industrial production and everyday life in other parts of the country.

Xinjiang’s energy transition is also extending into smaller-scale applications that are more closely connected to everyday life and local infrastructure. In remote desert areas and along major transport routes, renewable energy is increasingly being used to ensure the reliable operation of essential facilities. China Mobile Xinjiang has been developing solar-powered communication base stations in areas such as Aksu, exploring integrated solar and battery storage systems at key border locations in Wushi County, and deploying complementary wind-solar-storage systems in challenging environments along the Duku Highway. 

For communication stations located far from urban power grids, where conventional electricity supplies are limited, solar panels, wind turbines and energy storage systems can provide greater energy independence and improve reliability during extreme weather conditions. At the same time, initiatives combining photovoltaic power generation with agriculture and ecological restoration demonstrate that renewable energy development is no longer limited to large centralized power stations. It is gradually becoming part of rural production, infrastructure development and environmental protection.

Xinjiang’s renewable energy journey reflects both the rapid development of China’s wind and solar industries and the transformation of natural resource advantages into new drivers of regional growth. The economic landscape of this region was once defined primarily by farmland, pastures and traditional resource development. 

Today, it is increasingly shaped by wind turbines, photovoltaic panels, energy storage facilities and an expanding network of power transmission lines. The winds and sunshine across this vast territory are being transformed into new sources of industrial upgrading, national energy security and low-carbon development. Xinjiang is becoming, in every sense, fertile ground for China’s renewable energy future.

Source: sciencenet, cas, ceec, xjhb gov cn, xinhua, chinanews

The Global Journey of Chinese Papermaking and Its Impact on Arab and European Culture

0

Throughout human history, writing has preserved ideas, books have carried knowledge across generations, and paper has provided an essential foundation for the spread of learning. From ancient Chinese workshops to the scholarly centers of the Arab world and the printing houses of Europe, a technology originating in China crossed continents and transformed cultures. The spread of papermaking connected civilizations across Eurasia and profoundly influenced the development of human knowledge.

Before paper became widely available, people used various materials to record information. The ancient Egyptians made papyrus from the papyrus plant, while parchment, produced from animal skins, was widely used in Europe. In China, people wrote on oracle bones, bamboo and wooden slips, and silk. However, these materials had significant limitations. 

Bamboo slips were heavy, silk was expensive, and producing papyrus and parchment required considerable resources. As societies developed and cultural exchanges increased, people needed a lighter, more affordable, and more practical writing material. Paper gradually emerged to meet this demand.

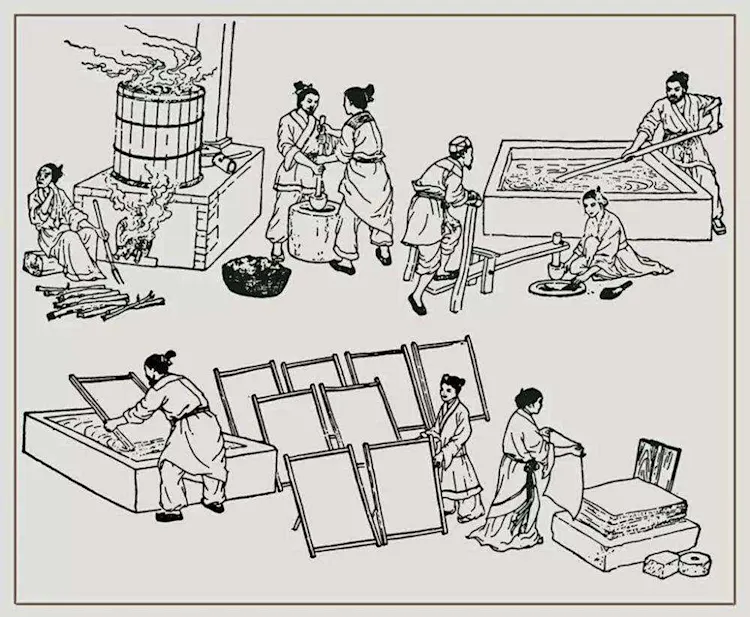
China was the birthplace of papermaking as an important technological tradition. Archaeological discoveries indicate that hemp-based paper existed in China during the Western Han dynasty. In the Eastern Han dynasty, Cai Lun improved existing papermaking techniques and presented his work to the imperial court around 105 CE. He used materials such as tree bark, hemp waste, old cloth, and discarded fishing nets to produce paper of better quality. By expanding the range of raw materials and improving the production process, these innovations helped make paper more practical and accessible.

The significance of papermaking extended far beyond writing. Paper was increasingly used for official documents, books, paintings, and packaging. It also provided an essential material foundation for the later development of printing. As the technology advanced, Chinese craftsmen accumulated considerable expertise, and paper became an important tool for cultural preservation and government administration. Through trade, migration, diplomatic contact, and warfare, papermaking gradually spread beyond China’s borders.

The westward spread of papermaking was a gradual process. By around the third century CE, paper had begun to move into Central Asia along routes connecting northwestern China with regions farther west. Archaeological discoveries in places such as Loulan, Dunhuang, and Turpan provide evidence of the use of paper and written documents along these routes. As merchants, travelers, and different communities interacted along the Silk Road, paper and knowledge of its production gradually traveled farther west, paving the way for the development of papermaking in the Arab world.

The Battle of Talas in 751 CE is often regarded as an important turning point in this history. The Tang dynasty forces fought the Abbasid Caliphate’s forces in Central Asia, and some Tang soldiers were captured. Historical accounts associate skilled papermakers among the captives with the subsequent spread of papermaking to Samarkand. Although the transmission of this technology was the result of a broader process of cultural contact rather than a single battle alone, the Battle of Talas remains a significant landmark in the story of papermaking’s westward journey.

Samarkand gradually developed into an important papermaking center. Local craftsmen adopted Chinese techniques and adapted them to regional materials and production conditions. The paper they produced was relatively affordable and suitable for writing. By the late eighth century, papermaking had also begun to develop in Baghdad under the Abbasid Caliphate, and workshops were subsequently established in other cities, including Damascus. 

As the technology spread throughout the Islamic world, production expanded and paper became increasingly common in administrative, commercial, and cultural life. The growing availability of paper helped create favorable conditions for the cultural flourishing of the Arab world. Before paper became widely used, parchment and papyrus were relatively expensive, limiting the copying and preservation of written works. More affordable paper reduced the cost of producing books and documents, making it easier to circulate administrative records, commercial accounts, religious texts, and scholarly works. As books became more accessible, private collections and libraries developed, allowing knowledge to reach a wider audience.

During the Abbasid period, Baghdad became a major center of scholarship and cultural exchange. Translation movements brought philosophical, medical, mathematical, and astronomical works from Greek, Indian, and Persian traditions into Arabic. Paper was not the sole cause of this intellectual flourishing, but it made copying, preserving, and exchanging large numbers of manuscripts considerably easier. 

Scholars could study earlier works, compare ideas, and build upon existing knowledge. The Arab world thus played an important role not only in preserving and transmitting knowledge from different civilizations but also in making original contributions to mathematics, medicine, astronomy, and other fields.

Papermaking subsequently continued its westward journey through North Africa and the Iberian Peninsula, bringing the technology into Europe. Spain became an important early center of European papermaking, followed by Italy, France, and other regions. Craftsmen adapted production methods to local materials and needs, and papermaking gradually expanded beyond its original centers. As production techniques improved, paper became more affordable and increasingly replaced traditional writing materials.

In Europe, the spread of paper transformed the conditions under which knowledge was produced and shared. During the Middle Ages, books were largely copied by hand, making them expensive and limiting their availability. As paper became more accessible, the costs of copying manuscripts and producing books declined. Schools, universities, religious institutions, and commercial communities gained a more practical means of recording and distributing information. 

By the fourteenth and fifteenth centuries, European papermaking had expanded considerably. When movable-type printing developed in Europe in the mid-fifteenth century, the combination of paper and printing enabled books to be reproduced and distributed on a much larger scale.

These developments helped create favorable conditions for the Renaissance and the Reformation. Classical literature, religious texts, scientific discoveries, and humanist ideas circulated more widely, exposing increasing numbers of people to new perspectives. Paper also became essential for government administration, commercial contracts, mapmaking, and scientific records. Over time, papermaking spread to the Americas and other parts of the world, becoming an indispensable component of modern civilization.

The history of papermaking is not simply a story of a technology moving from one region to another. It is a story of civilizations exchanging knowledge, adapting innovations, and creating new possibilities. 

Chinese craftsmen laid the foundations of papermaking; the Arab world developed the industry and supported the circulation of scholarship; and Europe expanded the reach of written knowledge through the growth of papermaking and printing.

A sheet of paper may appear fragile and insignificant, yet it carries centuries of history. By crossing geographical and linguistic boundaries, the paper connected China, the Arab world, and Europe, enabling ideas to be recorded, preserved, reproduced, and shared. The global journey of papermaking demonstrates that the progress of civilization rarely occurs in isolation. Instead, it grows through exchange, develops through adaptation, and continues through the collective contributions of different cultures.

Source: paper people, the paper, sohu, lingoace

China Grows Lab-Grown Diamonds, India Cuts Them, and America Sells Them: Who Captures the Value?

0

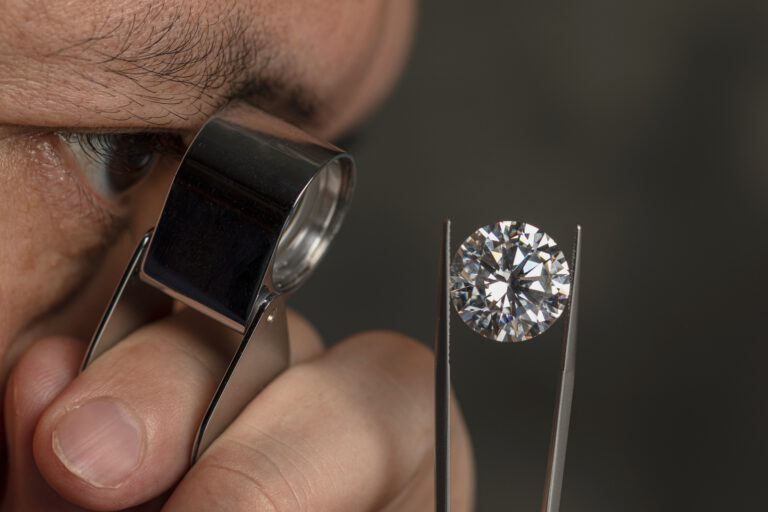
A one-carat lab-grown diamond displayed on a US retail website may have originated in Zhecheng, Henan Province, China, been cut and polished in Surat, India, and eventually entered an American retailer’s inventory. Along this global supply chain, the price of the same material changes dramatically. China has built substantial production capacity, yet it has not secured a corresponding share of the value created downstream.

In the first half of 2026, China’s average export price for rough lab-grown diamonds was approximately $8.94 per carat. After cutting and polishing in India, the average export price of finished loose stones rose to around $74 per carat. At US retailer Brilliant Earth, the median listed price for a one-carat round diamond with E color, VS1 clarity, Excellent cut, and an IGI certificate reached $796. 

These figures are not directly comparable measures of profit: cutting reduces weight, while grading, certification, logistics, marketing, and retailing all add costs. The specifications and commercial terms may also differ. Nevertheless, the price gap highlights a fundamental weakness in China’s position: the country can manufacture diamonds at scale but has limited influence over how they are processed, marketed, and priced for end consumers.

China’s competitive advantage rests on its manufacturing base. Both high-pressure, high-temperature (HPHT) and chemical vapor deposition (CVD) technologies have developed alongside a mature industrial ecosystem. Henan, in particular, has established a cluster spanning equipment manufacturing, crystal growth, testing, and processing. China’s rough lab-grown diamond production capacity reached approximately 25.2 million carats in 2025, accounting for around 63% of the global total.

Yet production capacity does not automatically translate into pricing power. According to She Dingshun, general manager of the Henan Lab-Grown Diamond Trading Center, India accounts for approximately 95% of global diamond cutting and polishing. China supplies the rough stones; India controls much of the processing and trading infrastructure; and Western markets capture value through branding, distribution, and retail. Chinese producers are concentrated in the most capital-intensive part of the chain, where cash flow is critical and bargaining power is weak.

The roots of this imbalance lie in the industrial nature of lab-grown diamonds. Unlike natural diamonds, whose supply depends on mineral deposits and lengthy mining cycles, lab-grown diamonds can be produced by adding equipment, improving growth processes, and increasing yields. Around 2021, some manufacturers achieved gross margins of 70%–80%, attracting investment and accelerating capacity expansion. Prices for premium rough stones subsequently fell from $150–160 per carat to around $30 in 2023 and approximately $10–15 in 2024.

Falling production costs should ordinarily reflect manufacturing progress. But when products are difficult to differentiate and sales channels are concentrated among a limited number of buyers, efficiency gains can translate into lower prices rather than higher profits. Chinese manufacturers, eager to secure orders and recover working capital, face pressure to undercut one another. Once one company lowers its price, competitors may follow to protect their market share. The result is a cycle in which greater capacity and better technology fuel further price declines.

The damage is already visible. Some factories in Henan suspended production when prices hit bottom in 2024. In the first half of 2025, the gross margin of lab-grown diamonds at China’s Power Diamond reportedly fell to 12.60%. The lesson is clear: expanding production alone can no longer guarantee sustainable growth.

India’s advantage lies in controlling the commercial links between production and consumers. Its established cutting and polishing workforce, trading networks, and customer relationships give buyers greater flexibility in choosing suppliers and negotiating prices. More concerning for China, India is also moving upstream. 

During fiscal 2024, India produced approximately 16 million carats of lab-grown diamonds. Indian company Kira announced plans to expand its CVD reactor fleet and extend its operations into cutting, polishing, and jewelry manufacturing. Government-backed research has also supported the development of domestic growth technologies and equipment. China’s manufacturing lead is therefore not guaranteed to last.

The strategic challenge is not simply to bring every processing step back to China. It is to gain greater control over how the entire value chain is organized. A proposed division of labor known as “Henan–Xinjiang–Shanghai” would combine crystal growth and rough-stone production in Henan, cutting and polishing in Shache County, Xinjiang, and trading, design, branding, and overseas market access in Shanghai. Shache County and Zhongzuan Network signed an industrial cooperation agreement in June 2026, with an initial group of approximately 60 trainees entering the training process.

Meanwhile, the Henan Lab-Grown Diamond Trading Center is developing shared inventory, trading events, and price indexes to improve transparency around quality, availability, and delivery schedules. These initiatives could help producers compete on consistent supply and product differentiation rather than price alone. Their real value, however, will depend on whether they attract sufficient buyers, generate credible transaction data, and secure repeat orders.

Moving downstream is not automatically profitable. Cutting and polishing require skilled labor, equipment investment, and a reliable order pipeline. Trading platforms need active participation from both buyers and sellers. Independent brands must shoulder the costs of design, marketing, distribution, and inventory. Vertical integration creates value only when the additional revenue exceeds the costs and risks of operating these new businesses.

A second opportunity lies beyond jewelry. Diamond, valued as a gemstone for its appearance and emotional significance, can also function as an advanced industrial material. Its exceptional thermal conductivity makes it a potential solution to one of the most pressing challenges in AI infrastructure: removing heat from high-power chips.

In February 2026, US company Akash Systems announced the delivery of NVIDIA H200 GPU servers incorporating its diamond-based cooling technology to Indian cloud provider NxtGen. The application is no longer merely theoretical, although commercial adoption still depends on performance, reliability, cost, and manufacturing consistency.

Chinese companies are also pursuing this market. Huifeng Diamond, based in Zhecheng, is expanding from diamond micropowders into high-thermal-conductivity materials, including diamond-copper composites and CVD diamond heat spreaders. The company has reported sample validation with major customers and initial small-scale production. 

Huanghe Whirlwind has developed polycrystalline diamond heat spreaders but has stated that these products have not yet had a material impact on its business. China National Machine Tool Corporation’s Guoji Jinggong has secured small-batch orders for diamond heat spreaders, primarily for defense applications, while its products for civilian thermal management remain under customer validation.

Industrial materials offer a different route to value creation. Customers care less about carat weight, color, and clarity than about thermal performance, reliability, service life, and consistency at scale. Qualifying for advanced supply chains requires extensive testing and customer validation, so technological breakthroughs alone are insufficient. But successful commercialization could give Chinese producers a more defensible competitive position than competing solely on the price of rough stones.

The central issue facing China’s lab-grown diamond industry is therefore not whether it can produce more diamonds, but whether it can capture more value from them. The supply chain from Henan to Surat to the United States reveals a gap between manufacturing strength and market power. Moving into trading, design, and branding could improve control over consumer-facing value, while advanced industrial applications could create new technological barriers to entry.

Neither path offers a shortcut. China’s next phase of growth will depend on converting production advantages into products customers recognize, technologies they trust, and orders that generate sustainable profits. Only then can the country move beyond leading in output to competing across the value chain.

Source: guancha, scmp, cw, the paper

China Puts AI to Work for Society Through Intelligent Waste Sorting

0

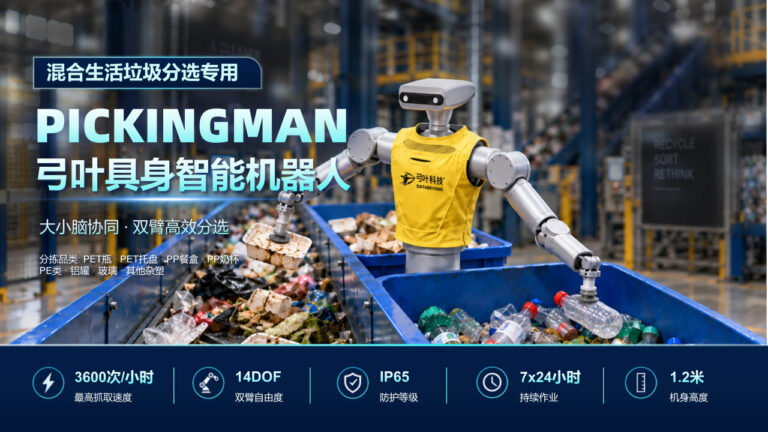
China is turning to artificial intelligence to solve one of the most difficult challenges in modern waste management: how to separate mountains of mixed waste efficiently and recover as many valuable materials as possible. By combining AI-powered recognition, hyperspectral imaging, robotics and automated sorting systems, Chinese companies are moving waste recycling beyond traditional manual sorting and toward a more precise, intelligent and industrialised process.

The scale of the challenge is enormous. According to China’s National Bureau of Statistics, the country’s urban areas collected and transported approximately 262 million tonnes of household waste in 2023. Much of this waste contains a complex mixture of plastics, metals, textiles, paper and organic materials. When these materials are mixed together, identifying and separating them becomes difficult, particularly when items are dirty, damaged or partially concealed. Valuable recyclable materials can consequently end up being incinerated or sent to landfill instead of being recovered.

Traditional sorting relies heavily on manual labour and mechanical equipment. Workers can identify obvious materials, while magnets and screens separate certain metals and objects by size. However, these methods struggle with complex waste streams, especially lightweight plastic films, multilayer packaging and mixed textiles. AI offers a new approach by enabling machines to recognise materials based on their visual characteristics and other measurable properties, making automated sorting more accurate and adaptable.

In Guangzhou, AI-assisted waste sorting has been tested at household waste transfer stations. The project has reportedly processed approximately 26,000 tonnes of untreated household waste. By identifying recyclable materials before the remaining waste moves to its next treatment stage, the system helps recover resources that might otherwise be lost. The project also demonstrates how AI sorting can be integrated into existing municipal waste infrastructure rather than requiring every part of the waste management system to be rebuilt from scratch.

In Dongguan, Guangdong Province, intelligent sorting technology is being applied to mixed waste at a larger industrial scale. AI-powered equipment identifies different objects moving along conveyor belts, allowing robotic systems or automated mechanisms to separate selected materials. Compared with conventional sorting, this approach can improve consistency, reduce reliance on manual labour and help facilities process complicated waste streams. Its value is particularly clear when dealing with materials that are difficult to distinguish by shape alone.

The technology behind these systems involves several layers. Computer vision first analyses images of waste items, identifying features such as shape, colour, texture and surface patterns. Deep-learning models are trained on large datasets containing examples of different waste categories, enabling them to recognise objects under changing conditions. Once an item has been identified, the system calculates its position and communicates with sorting equipment, which can use robotic arms, air jets or mechanical diverters to separate it from the waste stream.

However, recognising an object is not the same as identifying what it is made of. Two plastic items may look almost identical but consist of different polymers, which require different recycling processes. A dark plastic container, a dirty packaging film or a textile made from blended fibres can be particularly difficult to classify using ordinary cameras.

To address this problem, some advanced systems combine AI with hyperspectral imaging. Unlike conventional cameras, which capture a limited range of visible colours, hyperspectral cameras measure reflected light across many wavelengths. Different materials produce distinctive spectral signatures, allowing the system to distinguish certain plastics, fibres and other substances that look similar to the human eye. When these measurements are combined with machine-learning algorithms, sorting equipment can make more informed decisions about material composition.

This technology is also being explored in textile recycling. In Zhangjiagang, Jiangsu Province, specialised sorting equipment has been developed to identify and separate discarded textiles according to their material characteristics. This is important because clothing often contains mixtures of cotton, polyester, nylon and other fibres. Such mixtures can be difficult to recycle into high-quality new materials. More precise identification can improve the purity of sorted textiles and provide better-quality feedstock for downstream recycling processes.

Despite these advances, major technical challenges remain. Waste arriving at a sorting facility is rarely clean or uniform. Items overlap on conveyor belts, materials become contaminated with food or liquid, and flexible packaging can fold, tear or stick to other objects. AI models trained on carefully prepared images may perform less reliably in these unpredictable real-world conditions. Meanwhile, hyperspectral imaging and robotic sorting equipment must operate at high speeds without making the overall process prohibitively expensive.

Another challenge is that successful sorting does not automatically guarantee successful recycling. Recovered materials must meet the quality requirements of downstream processors, and the cost of cleaning, transporting and reprocessing them must be economically viable. A system may identify a material correctly but still fail to create a commercially valuable recycling stream if the material is too contaminated or difficult to process.

Chinese researchers and companies are therefore working to improve the entire process, from material recognition to physical separation and recovery. More diverse training datasets can help AI systems handle variations in waste composition. Improved sensors can provide more reliable material identification, while better robotic coordination can increase sorting speed and reduce missed or incorrectly classified items. Integrating these technologies with existing transfer stations and recycling plants also helps move intelligent sorting from isolated demonstrations toward practical, large-scale deployment.

The ultimate goal is not simply to make waste sorting faster. It is to recover materials that were previously too difficult or costly to separate, reduce the amount of waste requiring final disposal and return more resources to industrial production. Plastics may be directed toward mechanical recycling or, where appropriate, chemical recycling. Metals can re-enter manufacturing supply chains, while suitable textile fibres can become raw materials for new products. The actual outcome depends on the quality of the recovered material and the availability of suitable recycling facilities.

From Guangzhou’s household waste transfer stations to Dongguan’s intelligent mixed-waste sorting lines and Zhangjiagang’s textile-sorting equipment, China is pushing AI-powered recycling toward greater precision and efficiency. The most significant breakthrough is the ability to move beyond simply recognising rubbish and begin identifying the materials within it, determining their potential uses and directing them back into productive supply chains.

In the past, waste management focused primarily on collection, incineration and safe disposal. Today, the combination of AI, hyperspectral imaging and robotics is helping recover more valuable materials before they are lost in the final treatment process. The progress is not yet complete, and fully circular recycling remains difficult for many mixed and contaminated materials. But China is steadily tackling some of the hardest problems in industrial waste sorting.

When machines can identify different materials in tonnes of mixed waste and return them to the production chain, rubbish is no longer merely a burden to be disposed of. It becomes a resource waiting to be recovered. China’s ambition is to bring waste recycling to an unprecedented level of precision and efficiency, turning artificial intelligence into a practical force for extracting more value from every tonne of waste.

Source: databeyond, sthjj gz gov, china science communication, sina

Hong Kong’s First Five-Year Plan: Redefining Its Future Through Deeper Integration with Mainland China

0

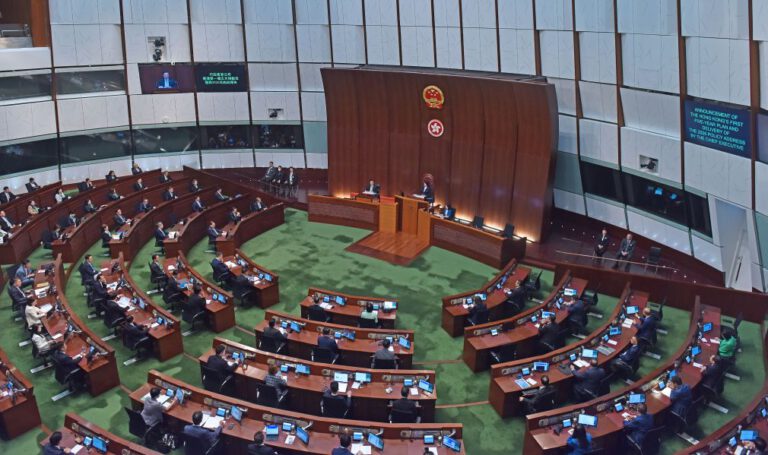
On September 16, 2026, the Hong Kong Special Administrative Region Government unveiled its first Five-Year Plan, covering the period from 2026 to 2030. The plan sets out priorities including consolidating Hong Kong’s position as an international financial, shipping, trade and aviation hub; developing its innovation and technology capabilities; accelerating the development of the Northern Metropolis; attracting global talent; improving livelihoods; and contributing more actively to national development. 

By establishing longer-term objectives alongside annual policy and budgetary arrangements, Hong Kong is seeking to move beyond incremental policymaking towards a more coordinated approach to economic and social transformation.

This does not mean abandoning Hong Kong’s market-oriented traditions or simply replicating the development model of mainland cities. On the contrary, the city’s value lies in its distinctive position under the “One Country, Two Systems” framework. Its international financial networks, common law system, free-port status, professional services and global talent pool remain important assets. The purpose of long-term planning is to bring these advantages together more effectively, ensuring that they complement the mainland’s industrial capacity, technological development and expanding domestic market.

Infrastructure provides the most visible evidence of how far cooperation between Hong Kong and the mainland has progressed. High-speed rail connections, cross-border roads, port facilities and increasingly integrated transport networks have reduced the time and friction involved in moving people and goods across the region. The Hong Kong section of the Guangzhou–Shenzhen–Hong Kong Express Rail Link has connected the city more closely with the national railway network, while the expansion of intercity railways across the Guangdong-Hong Kong-Macao Greater Bay Area is helping transform the region into a more integrated economic space.

The significance of these developments extends well beyond transport. As connectivity improves, businesses can distribute research, manufacturing, logistics and professional services across different cities more efficiently. Residents gain greater access to employment, education, healthcare and cultural activities. Cross-border cooperation is gradually evolving from occasional exchanges into an everyday economic and social reality.

Over the next five years, the Northern Metropolis is expected to become a major test of this transformation. Located along Hong Kong’s northern boundary, the area offers opportunities to develop new residential communities, innovation clusters and strategic links with Shenzhen. Proposed railway projects, including the Northern Link and its Spur Line, as well as the Hong Kong-Shenzhen Western Rail Link, could further strengthen cross-border connectivity if delivered according to plan.

Yet the success of these projects should not be measured simply by the number of kilometres of railway constructed or the amount of investment committed. The more important question is whether infrastructure can attract businesses, create quality employment, encourage research collaboration and generate sustainable economic activity. Without a clear industrial strategy, even large infrastructure investments risk becoming expensive assets that fail to deliver their full economic potential. Transport links must therefore be developed alongside land-use planning, commercial facilities, talent policies and cross-border coordination.

Economic exchanges between Hong Kong and the mainland demonstrate the scale of the opportunities. According to figures provided by Shenzhen Customs, trade between the mainland and Hong Kong increased from approximately RMB 420.87 billion in 1997 to RMB 2.6 trillion in 2025, representing average annual growth of 6.7 per cent. In the first five months of 2026, bilateral trade reached approximately RMB 1.4 trillion, up 48.6 per cent year on year. Trade passing through Shenzhen ports accounted for more than 70 per cent of the total cited in the figures.

These numbers highlight the continuing importance of Hong Kong within regional supply chains and cross-border commerce. However, a sharp increase over a limited period should not automatically be interpreted as a permanent growth trend. Global demand, trade policies, supply-chain restructuring and geopolitical uncertainty can all influence future performance. Hong Kong’s long-term competitiveness will depend on its ability to move beyond the expansion of existing trade flows and create new sources of value.

Innovation and technology represent one of the most promising avenues. Hong Kong has internationally recognised universities, research institutions, access to global capital and expertise in intellectual property and professional services. Shenzhen and other Greater Bay Area cities have developed strong capabilities in advanced manufacturing, electronics, artificial intelligence and commercial technology applications. Combining these strengths could create a more complete innovation ecosystem, connecting fundamental research with financing, product development, manufacturing and international markets.

Cooperation agreements between the Ministry of Science and Technology and the Hong Kong SAR Government have already established a foundation for closer collaboration in research, resource sharing, technology transfer and personnel exchanges. The first Five-Year Plan provides an opportunity to turn these arrangements into more practical outcomes. The Hetao Shenzhen-Hong Kong Science and Technology Innovation Co-operation Zone, universities and private enterprises could become important platforms for joint research and commercialisation.

Nevertheless, establishing laboratories and innovation parks is only the beginning. Hong Kong must address the persistent challenge of translating research into commercially viable products. Start-ups need access to capital, testing facilities, customers and affordable space in which to grow. Researchers need clearer pathways from academic discovery to commercial application, while businesses need confidence that intellectual property will be protected and cross-border collaboration can operate within workable regulatory frameworks. Without progress in these areas, innovation risks remaining a policy ambition rather than becoming a meaningful economic engine.

Finance will remain another pillar of Hong Kong’s development. The city has long served as an important gateway through which mainland companies access international capital and global investors participate in Chinese markets. Continued cooperation in stock markets, exchange-traded funds and other financial products can strengthen this role. Opportunities in renminbi internationalisation, green finance, digital finance and wealth management may also create new areas of growth.

However, Hong Kong’s status as an international financial centre cannot be taken for granted. Global interest rates, geopolitical tensions, regulatory changes and shifts in investor confidence can affect capital flows rapidly. Long-term planning can establish strategic direction, but it cannot substitute for market confidence. Maintaining a predictable legal and regulatory environment, deepening market liquidity and delivering high-quality professional services will remain essential. At the same time, financial development should support the real economy by helping innovative businesses raise capital and enabling productive investment, rather than relying solely on trading activity and asset valuations.

Cultural exchange, education and talent mobility are equally important to the future of regional integration. Hong Kong’s universities, cultural institutions and international networks complement the mainland’s expanding consumer market, technological industries and tourism resources. Cooperation in exhibitions, performing arts, film production, sporting events, research programmes and youth employment could help create a Greater Bay Area that functions not only as an interconnected economic region but also as a shared space for living, learning and cultural exchange.

Infrastructure may bring cities closer geographically, but sustained integration also requires mutual understanding and opportunities for ordinary people. Easier professional qualification recognition, more convenient cross-border services and greater access to education and employment can help ensure that regional cooperation delivers tangible benefits beyond major corporations and investors.

Despite these opportunities, Hong Kong faces several significant risks in implementing its first Five-Year Plan. The first is the gap between ambition and execution. Large infrastructure projects require substantial capital, lengthy construction periods and coordination across land use, environmental protection, public finances and regulatory approvals. If costs rise or implementation falls behind schedule, expected economic benefits may be delayed. The government will need transparent performance indicators, regular reporting and a willingness to adjust priorities when circumstances change. The number of projects launched should never be confused with the value they ultimately create.

The second risk concerns external dependence and economic concentration. Deeper integration with the mainland offers substantial advantages, but Hong Kong must also preserve and expand its international connections. Global trade tensions, changes in investment patterns and external policy restrictions could affect its traditional industries. A resilient strategy should therefore combine stronger mainland cooperation with continued engagement across international markets. Diversification into healthcare, green industries, professional services, technology and the creative economy could help reduce excessive reliance on a limited number of sectors.

A third challenge is ensuring that economic growth translates into improvements in everyday life. Housing affordability, an ageing population, youth employment and unequal access to opportunities remain important social concerns. New transport networks and innovation districts should ultimately create better jobs, more accessible public services and a higher quality of life. If investment generates impressive economic statistics without delivering meaningful improvements for residents, public confidence in the development strategy may weaken.

Hong Kong must also strike a careful balance between administrative coordination and market flexibility. Long-term planning can reduce uncertainty and align public investment with strategic objectives, but excessive rigidity could constrain entrepreneurship and discourage private-sector innovation. The city’s competitive advantage has historically depended on its ability to respond quickly to international opportunities. The challenge is to provide a clearer long-term direction without sacrificing that adaptability.

Ultimately, the importance of Hong Kong’s first Five-Year Plan lies not in the number of targets it contains, but in whether it can connect the city’s international advantages with the mainland’s industrial depth and the Greater Bay Area’s growing economic scale. Infrastructure can bring cities closer; technology can connect industries; finance and trade can mobilise resources; and cultural and educational exchanges can build the social foundations for lasting cooperation.

Hong Kong is not starting from scratch. It is building on decades of economic exchange, infrastructure development and institutional cooperation with the mainland. The next five years will test whether those foundations can support a new stage of development, one defined by stronger coordination, more effective execution and greater economic resilience.

The plan offers a roadmap, but its success will ultimately be judged by results. 

Railways must generate economic activity, research must lead to commercial innovation, finance must support productive investment, and regional integration must improve the lives of ordinary residents. If Hong Kong can turn these objectives into measurable achievements while preserving its openness, legal certainty and international outlook, its first Five-Year Plan could become a turning point in the city’s evolution from a gateway connecting China with the world into a more active contributor to the country’s long-term development.

Source: gdtzb gov cn, locpg gov cn, gov hk, cmab gov, cnbayarea, ndrc gov cn, most gov cn, southcn

What Does a 97.37% Conversion Rate Mean? China Advances CO₂-to-Jet-Fuel Technology for a Greener Aviation Future

0

Aviation is one of the hardest sectors to decarbonize. Unlike road transport, long-haul aviation cannot readily transition to battery-powered systems at scale, leaving conventional jet fuel essential for decades to come. Sustainable aviation fuel (SAF) is therefore a critical pathway toward reducing aviation emissions. When produced and certified to the required standards, SAF can be blended with conventional jet fuel and used in existing aircraft without fundamental engine modifications. Depending on its feedstock and production pathway, SAF can significantly reduce lifecycle greenhouse gas emissions.

For China, SAF is not merely an environmental issue; it is also a question of energy security, industrial upgrading and international competitiveness. With annual aviation fuel consumption estimated at around 30 million tonnes, even a modest blending rate could generate substantial demand. International aviation climate initiatives and blending requirements in markets such as the European Union are accelerating the transition. China has launched SAF application trials and is expanding its production capacity, but large-scale commercialization remains constrained by high costs, limited feedstock availability and the need for reliable supply chains.

Today, commercial SAF production relies heavily on biological feedstocks such as waste oils and fats, processed through technologies including hydrotreatment. Yet these feedstocks are limited and cannot necessarily meet future aviation demand on their own. This is why routes that combine carbon dioxide with green hydrogen are attracting attention. By using captured CO₂ and hydrogen produced with renewable energy, synthetic aviation fuel could expand beyond the constraints of conventional biomass feedstocks. Its climate benefits, however, depend on the carbon intensity of hydrogen and electricity, process energy consumption and lifecycle emissions.

China has recently made an important advance in this field. A thousand-tonne-scale CO₂-to-SAF technology, led by a team from Tsinghua University and developed with industry partners, passed a scientific and technological achievement evaluation organized by the China Petroleum and Chemical Industry Federation. 

The researchers developed a bifunctional catalyst combining nanoscale spinel and molecular sieves, coordinating CO₂ activation and carbon–carbon coupling before subsequent hydrogenation produces jet-fuel components. They also addressed key engineering challenges involving high-pressure fluidized-bed reactors, moving the process beyond laboratory chemistry toward industrial demonstration.

The breakthrough matters because it addresses two central questions for SAF: whether the carbon feedstock can be expanded and whether the conversion process can operate efficiently. According to the project data, the pilot plant in Meishan, Sichuan, has accumulated more than 2,000 operating hours. During a continuous 72-hour assessment, it ran steadily at full load, achieving a total CO₂ conversion rate of 97.37% and a selectivity of 92.37% for jet-fuel components. 

The resulting fuel reportedly met all indicators under China’s GB 6537 – 2025 No. 3 Jet Fuel Standard. The evaluation committee judged the overall technology to be internationally advanced and suitable for the design and construction of a ten-thousand-tonne-scale industrial demonstration.

Economics will ultimately determine whether technology can transform the market. Under the project’s stated assumptions for green hydrogen, CO₂, electricity and steam prices, estimated production costs are over 1000 euros per tonne, with a projected static payback period of around 2.5 years for a plant producing 100,000 tonnes annually. These are scenario-based estimates, not guaranteed commercial outcomes. Green hydrogen prices, renewable electricity availability, capital expenditure, energy consumption and future SAF prices will all shape actual profitability.

This breakthrough does not mean aviation’s decarbonization challenge has been solved. Rather, it offers China another potential way to expand SAF supply. If subsequent industrial demonstrations confirm long-term operational stability, competitive costs and genuine lifecycle emissions reductions, CO₂-to-SAF technology could complement biomass-based pathways. 

Its broader significance lies not simply in converting a greenhouse gas into aviation fuel, but in linking carbon capture, green hydrogen, renewable energy and aviation into an integrated industrial ecosystem. Ultimately, its success will depend not only on conversion rates above 97%, but on whether it can deliver certified aviation fuel that is affordable, scalable and demonstrably lower-carbon.

Source: global net zero, tsinghua, paper people, sohu, ideacarbon

Russia and America: Rivals in Power, Twins in Exceptionalism

0

Russia and the United States are often portrayed as ideological opposites: one defends a sovereign civilization against Western dominance, while the other claims to uphold a liberal international order. Yet beneath their differences lies an uncomfortable similarity. Both have powerful traditions of national exceptionalism that their history, identity, and global mission make them unlike other countries, and that ordinary rules may not always apply to them.

This does not mean that Russia and America are politically identical. Their institutions, civil liberties, and systems of accountability differ substantially. Nor does it mean that their actions carry equal consequences in every situation. The deeper parallel lies elsewhere: both countries have political traditions that can turn national identity into a source of unlimited entitlement. Each can see itself not simply as one state among many, but as a country with a special right to shape the world around it.

Two tigers may share a mountain in theory. In practice, however, when both believe the mountain is theirs by historical right, coexistence becomes difficult. The rivalry between Russia and America is therefore not merely a struggle over territory, security, or economic advantage. It is also a collision between competing claims to exceptional status.

Russia’s civilizational argument has a long intellectual history. In the nineteenth century, the Russian thinker Nikolay Danilevsky challenged the idea that European civilization represented a universal model for humanity. He argued that different cultural and historical worlds developed according to their own principles, and that Russia and the Slavic peoples constituted a distinct civilizational type rather than an incomplete version of Western Europe.

The importance of this argument was not simply that Russia was different. It was that Russia’s difference could be presented as a source of independent historical legitimacy. If the West did not possess a universal standard by which all societies should be judged, Russia could reject Western criticism and claim the right to follow its own path.

Later Eurasianist thinkers developed this line of thought, emphasizing Russia’s position between Europe and Asia and portraying it as the center of a distinctive historical and cultural space. These ideas did not always lead to the same political conclusions, but they offered an enduring alternative to the belief that Russia’s future depended on becoming more like the West.

The collapse of the Soviet Union gave this tradition renewed relevance. For many Russians, the 1990s brought not only economic hardship and political instability, but also a profound loss of international status. The expectation that Russia would gradually integrate into a Western-led order did not produce the partnership many had hoped for. NATO enlargement, conflicts over the post-Soviet space, and disagreements about the meaning of European security reinforced the perception among Russian elites that the West was willing to accept Russia only on subordinate terms.

That perception was not the only possible interpretation of the post-Cold War settlement, and it does not justify Russia’s subsequent use of force against its neighbors. But it helps explain why civilizational arguments gained political traction. They offered a way to reinterpret national weakness as historical distinctiveness: Russia was not failing to become Western; it was supposedly following a different and equally legitimate path.

Under Vladimir Putin, this language has become increasingly important to the state’s account of itself. Russia is presented as a sovereign civilization with its own moral traditions, historical experience, and security requirements. Western liberalism is portrayed not simply as a competing political philosophy, but as an external influence that threatens Russia’s identity and cohesion.

The problem begins when this claim moves from cultural independence to geopolitical entitlement. A country has every right to preserve its language, traditions, and institutions. It does not follow that it has a special right to determine the political choices of neighboring countries. Ukraine, for example, has its own national identity and right to political independence. Russia’s historical ties to Ukraine cannot erase that sovereignty.

Civilizational language can blur this distinction. If a neighboring country is described as belonging naturally to a larger historical space, its independent choices may be treated as artificial, illegitimate, or the result of foreign manipulation. The argument then becomes circular: Russia must control its neighborhood because it is a distinct civilization, and its civilization must be protected by maintaining control over its neighborhood.

Here the rhetoric of historical destiny becomes a justification for power. National identity, which should help people understand their past, is transformed into a political claim over other people’s futures.

America’s exceptionalism has a different history and a different political setting, but it contains a related tension. The United States has often described itself as a country founded on universal principles: individual liberty, representative government, equality before the law, and the right of peoples to political self-determination. These ideals have inspired movements for freedom around the world and remain central to America’s national identity.

Yet American political culture has also nurtured the conviction that the United States occupies a unique position in history. If America represents a universal ideal, its leaders may come to believe that American power serves humanity as a whole. Actions taken in the national interest can then be presented as actions taken for the benefit of the international community.

This is one of the enduring contradictions of American foreign policy. Universal principles can restrain power, but they can also be used to legitimize it. Washington has defended international institutions and alliances, yet it has also resisted rules it considers incompatible with American freedom of action. It has condemned other governments for violating international norms while at times interpreting those norms selectively when American interests are at stake.

The “America First” approach makes this contradiction more explicit. It questions the assumption that the United States should bear disproportionate costs for maintaining the international order, and it treats alliances, trade arrangements, and multilateral commitments more openly as instruments to be judged by their direct benefits to America.

There are legitimate reasons for any government to reconsider its international commitments. Alliances should not be immune from debate, and international institutions can be inefficient or unfair. But a different principle is at work when a country claims the benefits of an international order while reserving the right to disregard its constraints whenever they become inconvenient.

In that respect, the Russian and American narratives can begin to resemble each other. Russia invokes civilizational sovereignty to resist what it sees as Western domination. America invokes national sovereignty to resist obligations it sees as unfair or contrary to its interests. Their histories and political systems remain different, but both narratives can place national discretion above shared rules.

This is the paradox of exceptionalism: two countries may disagree about almost everything and still share the belief that their own status entitles them to special treatment. Their rivalry becomes particularly dangerous when each interprets the other’s independence as a threat to its own rightful position.

For Russia, the expansion of Western influence near its borders can be portrayed as an existential challenge to its civilization. For the United States, the emergence of a rival power capable of challenging American leadership can be portrayed as a threat to the stability of the international order. Both countries may sincerely believe that they are acting defensively. Yet when each side defines security as the preservation of its own privileged position, measures presented as defensive by one are experienced as offensive by the other.

This dynamic creates a familiar spiral. One power strengthens its military position to protect its interests; the other sees that move as evidence of hostile intent and responds in kind. Each side points to the other’s response as proof that its original fears were justified. Over time, compromise becomes politically harder because concessions appear to betray not merely a practical interest but a national mission.

The result is a world in which geopolitical competition acquires the emotional force of a struggle over identity and historical legitimacy. Negotiations that might resolve specific disputes become more difficult when each side believes that accepting limits would mean surrendering its rightful place in history.

The consequences extend beyond Russia and America. As international competition intensifies, governments elsewhere may increasingly use the language of civilization, sovereignty, and national destiny to justify their own ambitions. International institutions then risk becoming arenas in which powerful states defend their privileges rather than mechanisms through which all states accept common constraints.

This is especially troubling in an age of rapid technological change. Artificial intelligence, cyber conflict, climate change, pandemics, and the governance of global markets all create problems that no country can manage entirely on its own. Even the most powerful state depends on information, cooperation, and standards that cross national borders. If every government treats international rules as optional whenever they conflict with its own exceptional mission, collective action becomes much harder.

None of this requires the world to adopt a single political model. Cultural diversity is real, and the assumption that every society must follow one historical path has often produced arrogance and intervention. Countries should have room to develop their own institutions and preserve their own traditions. The mistake is to confuse the right to be different with the right to dominate.

The same distinction applies to national sovereignty. Sovereignty protects a country’s independence; it does not grant an unlimited license to interfere in the independence of others. Nor should universal principles be used selectively as a cover for the ambitions of powerful states. If international rules are to command respect, they must apply consistently, including when compliance is inconvenient for the strongest countries.

Russia and America do not need to become alike in order to coexist. They do, however, need to accept that neither possesses an exclusive right to define the international order. A stable world cannot depend on the assumption that one great power is destined to lead or that another is entitled to control its neighbors. It requires the recognition that national interests, however important, exist alongside the legitimate interests and rights of other nations.

The real danger is not that Russia and America are too different. It is that, in different ways, both can be drawn toward the same conviction: that their own exceptional status entitles them to a freedom of action denied to others.

Two tigers may not be destined to fight simply because they are tigers. But when each believes that the mountain belongs to it alone, conflict becomes much more likely. The task of international politics is not to decide which tiger has the greater historical claim. It is to establish rules that prevent either from claiming the entire mountain.

Only when great powers accept limits on their own exceptionalism can national independence coexist with international order. Without those limits, the language of civilization and national greatness may promise dignity and security, while leading instead to suspicion, confrontation, and an increasingly dangerous struggle for dominance.

Source: chn belta, brookings, riddle russia, fpri, cscr