7.7 C
Berlin
Friday, October 30, 2026
spot_img
Home Blog Page 3

How China’s Coastal City of Yangjiang Is Emerging as a Global Offshore Wind Power Hub

0

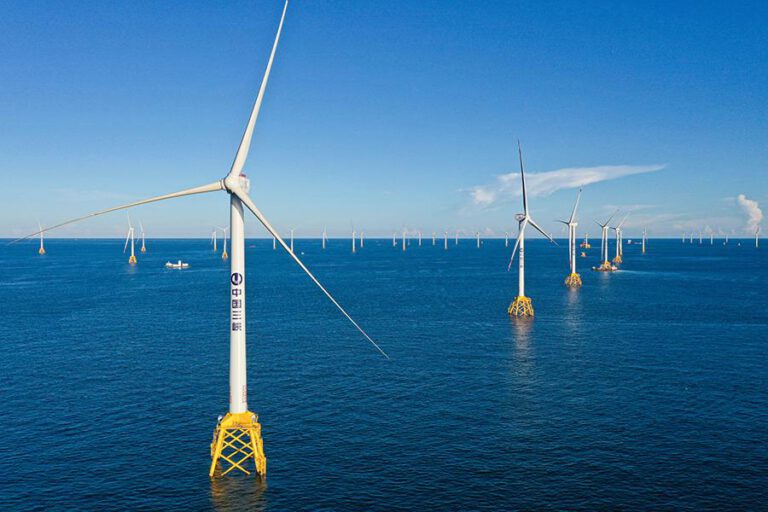
Along the coast of the South China Sea, rows of offshore wind turbines turn steadily in the sea breeze, transforming abundant wind resources into clean electricity. From large-scale offshore wind development and advanced equipment manufacturing to deep-sea technological innovation and international exports, Yangjiang, a coastal city in western Guangdong Province, is accelerating the development of a comprehensive green energy industry. By integrating renewable energy with advanced manufacturing, the city is forging a distinctive path toward industrial transformation and sustainable growth.

A major offshore wind power project in Yangjiang recently reached a significant milestone. In waters off Yangxi County, the subsea cable transmission project serving the China Three Gorges Corporation’s Yangjiang Qingzhou V and VII offshore wind farms successfully completed a key stage of construction. The ±500-kilovolt flexible direct-current submarine cables passed their withstand-voltage tests, while construction of the offshore converter station platform was completed. The entire transmission system is now ready for energization, marking a major step toward connecting the project to the power grid.

The progress reflects not only the development of a major infrastructure project but also China’s broader efforts to advance offshore wind power into deeper waters, increase generating capacity and improve transmission efficiency. Supported by abundant marine wind resources, an increasingly complete industrial supply chain and growing technological capabilities, Yangjiang is evolving from an offshore wind development base into an industrial hub integrating energy production, equipment manufacturing, research and development, port logistics and green energy applications.

Yangjiang’s rise as an offshore wind power center began with its natural advantages. The city has a coastline stretching approximately 458 kilometers and a marine area of around 11,900 square kilometers. Favorable wind conditions, extensive offshore resources and proximity to the Guangdong-Hong Kong-Macao Greater Bay Area, one of China’s major electricity consumption centers, provide a strong foundation for large-scale offshore wind development.

In September 2017, the 400-megawatt Yangjiang Nanpeng Island offshore wind power project developed by China General Nuclear Power Group received approval, marking the beginning of Yangjiang’s journey toward large-scale offshore wind development. Over the following years, major energy companies invested in a growing portfolio of projects, creating a development model in which offshore wind farms drive demand for equipment manufacturing and related services, while the expansion of the industrial supply chain further strengthens the city’s capacity to develop and operate wind power projects.

Today, Yangjiang has a planned offshore wind power capacity of 20 gigawatts, with more than 7 gigawatts connected to the grid. Projects under construction or planned to begin construction account for approximately 6 gigawatts, placing the city among China’s leading offshore wind development centers. According to local development plans, Yangjiang’s grid-connected offshore wind capacity is expected to exceed 13 gigawatts in 2026, potentially making it the country’s first offshore wind power base with more than 10 gigawatts of installed capacity.

Behind these figures lies a deliberate effort to build an integrated industrial ecosystem. Yangjiang has attracted major energy developers, including China Three Gorges Corporation, China Huadian Corporation and China General Nuclear Power Group, while encouraging manufacturers and supporting businesses to establish local operations. This approach has helped transform project investment into a broader industrial development opportunity, creating demand for wind turbines, blades, submarine cables, towers, offshore engineering equipment and technical services.

The Guangdong (Yangjiang) International Wind Power City has become a central platform for this transformation. A growing number of manufacturers are establishing operations in the area, strengthening local capabilities across the wind power value chain. From turbine assembly and component manufacturing to cable production, structural engineering and maintenance services, the industrial network is becoming increasingly comprehensive.

This development is changing the economic significance of offshore wind power in Yangjiang. The industry is no longer defined solely by electricity generation. It is also creating opportunities in advanced manufacturing, engineering services, technological innovation and international trade. As the supply chain becomes more complete, companies benefit from closer coordination, improved delivery efficiency and stronger access to technical support.

The development of public service platforms has further strengthened the industrial ecosystem. Yangjiang is gradually establishing a service network known as “One Port and Four Centers,” encompassing an offshore wind equipment logistics and maintenance hub, a national quality inspection and testing center for offshore wind equipment, a big-data center, an integrated operations and maintenance center, and the Yangjiang Offshore Wind Power Laboratory. Together, these facilities provide support throughout the equipment lifecycle, from research and testing to manufacturing, installation and maintenance.

Universities and research institutions are also playing an increasingly important role. Guangdong Ocean University’s Yangjiang campus and other local research organizations are working with companies through joint laboratories, practical training programs and collaborative research initiatives. These partnerships help develop skilled professionals while bringing industrial challenges directly into the research environment.

As Yangjiang’s industrial base expands, technological innovation is becoming increasingly important. Offshore wind development is moving toward deeper waters and more distant offshore locations, where wind resources can be substantial but engineering conditions are considerably more demanding. Greater water depths, stronger waves, severe typhoons and more complex maintenance requirements place higher demands on equipment reliability, structural design and operational efficiency.

Floating offshore wind technology offers a promising solution. Unlike conventional fixed-bottom turbines, floating turbines are supported by buoyant platforms secured to the seabed with mooring lines. This approach can reduce the need for expensive seabed foundations and make wind power development possible in deeper waters.

Yangjiang has become an important testing ground for this technology. The Three Gorges-led “Three Gorges Pioneer” floating offshore wind turbine, which entered operation in late 2021, demonstrated the potential of floating wind technology in typhoon-prone waters. More recently, the “Mingyang Tiancheng,” a floating wind power unit featuring two turbines mounted on a single platform, was connected to the grid in the Qingzhou waters of Yangjiang. With a combined turbine capacity of 16.6 megawatts, the installation represents a significant advance in large-scale floating wind technology.

These projects provide valuable experience in platform stability, typhoon resistance, intelligent monitoring and long-term offshore operations. They also help establish a technical foundation for the future commercial deployment of floating wind farms.

Power transmission is another critical challenge as offshore wind farms move farther from shore. Traditional alternating-current transmission can face limitations in long-distance submarine cable applications, while high-voltage direct-current systems offer advantages for transmitting large amounts of electricity over extended distances.

The Yangjiang Qingzhou V and VII offshore wind project demonstrates how this technology can support deepwater development. With a planned generating capacity of 2 gigawatts and a location approximately 70 kilometers offshore, the project uses a ±500-kilovolt flexible direct-current transmission system. Electricity generated by the turbines is collected through submarine cables and sent to an offshore converter station, where it is converted into high-voltage direct current. It is then transmitted to an onshore control center before being converted back into alternating current for connection to the grid.

The project includes two direct-current submarine cables, each more than 90 kilometers long. Once fully operational, it is expected to supply approximately 6 billion kilowatt-hours of clean electricity to the Greater Bay Area annually and reduce carbon dioxide emissions by around 5 million tonnes a year.

The project illustrates how advances in offshore generation and transmission must progress together. Larger turbines alone cannot unlock the full potential of deepwater wind resources; reliable transmission infrastructure is equally essential. By developing both technologies, Yangjiang is helping establish practical solutions for the next stage of offshore wind expansion.

Innovation is also taking place in materials science, equipment testing and intelligent operations. Offshore wind turbines operate in environments characterized by high humidity, salt corrosion, powerful winds and persistent wave action. These conditions demand materials with exceptional strength and durability, as well as monitoring systems capable of identifying equipment problems before they lead to failures.

Local research teams have been working on high-performance underwater grouting materials, submarine cable protection systems, floating wind technology and intelligent maintenance solutions. Research institutions and companies are increasingly collaborating to address engineering problems identified in real projects, allowing promising technologies to be tested and applied more quickly.

This close connection between research and industrial practice is helping Yangjiang move beyond expansion driven primarily by installed capacity. The city is building capabilities in technological development, product reliability and full-lifecycle equipment management, all of which will be essential to maintaining competitiveness as offshore wind development becomes more technically demanding.

Another major priority is ensuring that the electricity generated offshore can be transmitted efficiently and consumed reliably. Wind power output varies with weather conditions, creating challenges for grid stability and electricity balancing as installed capacity increases. Yangjiang’s diversified energy mix, which includes wind, thermal, hydroelectric, nuclear and solar power, provides favorable conditions for developing a more flexible power system.

One approach is to coordinate wind power generation with controllable thermal power generation. When wind output is high, thermal generation can be reduced; when wind output declines, thermal generation can be increased to help balance electricity supply. Energy storage provides another means of managing fluctuations. Electricity can be stored when wind generation is abundant and released when demand rises or transmission capacity becomes constrained.

Yangjiang has begun applying these approaches through coordinated power generation and independent energy storage projects. Such measures can help reduce electricity curtailment, improve grid flexibility and make better use of renewable energy resources.

The city is also exploring ways to turn its green electricity resources into an advantage for advanced manufacturing. As international markets increasingly emphasize carbon footprints and sustainable supply chains, access to reliable low-carbon electricity is becoming an important consideration for export-oriented industries.

Yangjiang is promoting green industrial parks, direct green electricity supply and carbon management systems to encourage closer integration between renewable energy and manufacturing. These initiatives aim to attract businesses involved in energy storage, clean energy equipment and other emerging industries while helping existing manufacturers reduce their carbon emissions.

This approach expands the role of offshore wind power beyond electricity generation. Renewable energy can become the foundation for a broader industrial transformation, supporting energy storage, hydrogen production, low-carbon manufacturing and other emerging applications. By increasing the local utilization of green electricity, Yangjiang can create additional economic value while contributing to the decarbonization of industry.

Yangjiang’s industrial capabilities are also opening new opportunities in international markets. As countries accelerate the energy transition, demand for wind power equipment and related engineering services continues to create opportunities for manufacturers with competitive products and reliable delivery capabilities.

The city is increasingly using its manufacturing base and port infrastructure to connect local production with overseas projects. In September 2025, the vessel Tianhui departed Yangjiang Port carrying nine sets of wind turbine equipment bound for Italy. Produced by a local manufacturer, the shipment included turbines, hubs, blades, towers and associated components, with a total value exceeding RMB 130 million.

Yangjiang Port has also handled shipments of complete wind turbine equipment destined for Vietnam. These operations demonstrate the growing ability of the port to accommodate oversized, heavy industrial cargo and support the export of high-value renewable energy equipment.

Transporting wind power equipment requires specialized port facilities, heavy-lifting capacity, careful vessel scheduling and efficient customs clearance. Yangjiang has been improving its port infrastructure and introducing more coordinated services for wind equipment exports. These efforts help reduce logistics costs, improve shipment efficiency and strengthen the city’s ability to serve international customers.

The growing export business represents an important extension of Yangjiang’s industrial development. Offshore wind projects generate demand for equipment, manufacturing attracts suppliers and technical services, research institutions support innovation, and port logistics connect the entire industrial chain with global markets. Together, these elements are helping establish Yangjiang as a participant in the international division of labor in the wind power industry.

Despite its progress, Yangjiang still faces significant challenges as offshore wind development moves farther into the deep sea. Floating wind technology requires further improvement before it can be deployed at a much larger commercial scale. Offshore construction and maintenance remain expensive, while the long-term reliability of equipment operating in harsh marine environments requires continued testing and technological development.

The local supply chain also needs to strengthen its capabilities in certain high-value components, including advanced bearings, gearboxes and specialized offshore engineering equipment. Improving domestic production of these components would enhance supply chain resilience and increase the proportion of value retained within the local economy.

Addressing these challenges will require continued investment in research and development, closer collaboration between manufacturers and research institutions, and improvements in offshore installation, inspection and maintenance services. At the same time, the expansion of wind power capacity must be coordinated with grid development, energy storage and electricity consumption to ensure that new generating capacity can be used efficiently.

Looking ahead, Yangjiang plans to further strengthen its industrial supply chain, improve deepwater maintenance capabilities and accelerate the development of a comprehensive green energy system. Its longer-term ambitions include integrating wind power with other renewable energy sources, energy storage and hydrogen production, while using clean electricity to support the development of low-carbon industrial clusters.

From the approval of its first major offshore wind project in 2017 to the development of an integrated industrial ecosystem today, Yangjiang has undergone a remarkable transformation in just eight years. The city is turning marine wind resources into clean electricity, project demand into manufacturing capacity, research into practical technological advances, and local production into an increasingly international business.

As offshore wind technology continues to advance and global demand for clean energy grows, Yangjiang is positioned to play an increasingly important role in China’s offshore wind industry. Its experience demonstrates how natural resource advantages can be transformed into industrial strength through coordinated investment, technological innovation, infrastructure development and market expansion.

From nearshore waters to the deep sea, from electricity generation to advanced manufacturing, and from local production to global markets, Yangjiang is pursuing a development model that links the energy transition with industrial upgrading. Along the shores of the South China Sea, the city is turning the power of the wind into a lasting source of economic opportunity and a contribution to a greener future.

Source: xinhua, people, 21jingji, nfnews, yicai
The Pinglu Canal Opens: From a Landmark Infrastructure Project to a New Era of River–Sea Connectivity

0

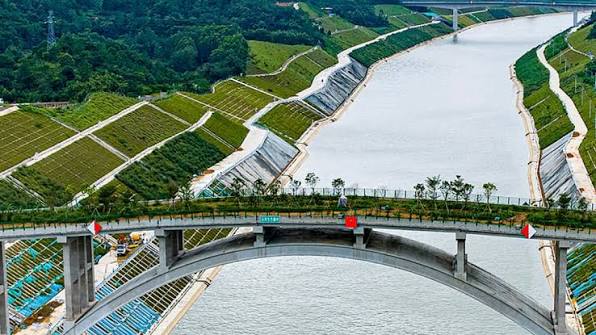
On September 16, after four years of construction and an investment of approximately RMB 72.7 billion, the Pinglu Canal officially opened to navigation. Stretching 134.2 kilometers, the canal begins at the mouth of the Ping Tang River in Hengzhou, Nanning, Guangxi, passes through Luwu in Lingshan County, Qinzhou, and follows the Qinjiang River to the Beibu Gulf. It is the first inland waterway canal since the founding of the People’s Republic of China to be centrally planned and developed at the national level to connect inland waterways directly with the sea. 

Built to Class I inland waterway standards, the canal can accommodate vessels of up to 5,000 tonnes. Its significance extends beyond the opening of a new shipping route: it has the potential to reshape logistics networks, industrial development and regional openness across southwestern China, while establishing new approaches to modern canal engineering and maritime safety management.

On September 16, the vessel Guangxing 798 departed from Berth 10 at the Liujing operating area of Nanning Port, beginning its maiden voyage through the Pinglu Canal to Yangpu Port in Hainan. The departure marked a major step in transforming Nanning Port from a traditional inland port into a departure point and distribution hub for river–sea intermodal transport. It also created a new southern maritime outlet for cargo originating in Guangxi and neighboring provinces and municipalities, including Yunnan, Guizhou, Sichuan and Chongqing.

For years, cargo from southwestern China heading south toward overseas markets has relied primarily on railways, highways and the Xijiang River shipping network, often passing through ports in Guangdong. The Pinglu Canal offers an alternative route, allowing vessels to travel from the Xijiang River through the canal to Qinzhou Port and the Beibu Gulf. This is expected to shorten shipping distances and improve access to Southeast Asia and other international markets.

According to shipping and logistics companies operating in the region, the journey from Nanning to Hai Phong, Vietnam, via the canal could take approximately one day, while transport to Ho Chi Minh City could take around three days. Shipping to other Southeast Asian destinations could generally be completed within a week. For businesses in Sichuan, combining rail transport with inland waterway shipping has also demonstrated the potential to reduce container transportation costs compared with previous rail-based routes.

The canal’s economic value is increasingly extending beyond transportation to industrial development. Businesses associated with Nanning Port have noted that expectations of lower logistics costs and easier access to overseas markets have become important considerations in investment decisions. Major projects, including BYD’s battery production facilities and Sun Paper’s integrated forestry, pulp and paper operations, illustrate how the canal’s development can encourage industrial investment along its route.

As the port’s cargo hinterland expands beyond its immediate surroundings to include mineral resources from Yunnan and Guizhou and automotive components from the Chengdu–Chongqing region, a more diversified cargo base is expected to emerge. Products such as paper, new-energy equipment, battery storage units and industrial components could benefit from improved connections between inland production centers, coastal ports and international markets.

Yunnan is also preparing to capitalize on the new route. The construction of Funing Port in Wenshan has progressed alongside the Pinglu Canal project, while Yunnan is strengthening coordination with Guangxi and Guangdong on navigation management, emergency response, vessel standardization, port operations and service standards. In the longer term, closer integration of railways, inland waterways and maritime shipping could give southwestern China more flexible transport options and strengthen connections between regional industries and global supply chains.

However, the opening of the canal is only the beginning. Its long-term economic impact will depend on whether cargo volumes can grow sustainably, industries can upgrade along the route, and port and shipping services can develop into an integrated network. For businesses, choosing a transport route involves more than comparing freight rates. The number of cargo transfers, delivery schedules, risks of damage, customs procedures and reliability during extreme weather all influence logistics decisions. The canal must therefore demonstrate its practical advantages in transfer efficiency, lock transit times and container handling before companies can fully transition from established transport arrangements.

Future development will require not only improvements to port facilities and railway connections, including the railway-port facilities at Liujing, but also a shift in the role of shipping and logistics companies. Rather than simply providing berths and transportation, they will need to offer end-to-end supply chain services covering procurement, warehousing, transportation, delivery and overseas distribution. 

Integrated multimodal transport documentation, through-freight pricing, cargo tracking, bonded warehousing and supply chain finance could help reduce overall logistics costs, lower inventory requirements and improve delivery reliability. Establishing stable and replicable cargo categories and shipping routes will be more important in the early stages than pursuing short-term growth in throughput alone.

As an artificial waterway, the Pinglu Canal also offers engineering advantages over natural rivers. Its curves, channel dimensions and bridge clearances have been designed around the requirements of vessels carrying up to 5,000 tonnes. With hundreds of advanced technical indicators supporting its operation, the canal represents more than a conventional excavation project. It embodies an approach to modern navigation that combines purpose-built infrastructure with intelligent and data-driven management, making vessel movements more predictable and controllable.

Alongside construction, the development of a dedicated regulatory framework has become another major achievement. Because the Pinglu Canal connects inland waterways directly with the sea, it must accommodate two distinct navigation systems. Differences between inland and maritime rules have historically created uncertainties regarding jurisdiction, vessel eligibility and collision avoidance at river–sea boundaries. To address these challenges, the Guangxi Maritime Safety Administration led the drafting of the Regulations on Navigation Safety Management of the Pinglu Canal, establishing a dedicated framework for safe navigation.

The regulations designate the Qinjiang Bridge on the G75 Lanzhou–Haikou Expressway as the boundary between inland waters to the north and maritime waters to the south. They also establish a designated “equivalent Class A navigation zone” in specific waters of Qinzhou Bay, allowing eligible inland vessels to enter the designated maritime area once the required certification endorsements have been obtained. Across the canal, a unified traffic-separation system and common navigation rules are intended to reduce conflicting interpretations between inland and seagoing vessels.

Another important innovation is the conversion of general safety principles into measurable operating requirements. The regulations specify navigation speeds, minimum safety distances, under-keel clearance, bridge clearance and thresholds for suspending navigation during adverse weather. They also prohibit several high-risk maneuvers. By replacing vague instructions with quantifiable standards, the framework seeks to make safety decisions more consistent, transparent and enforceable.

From the completion of the physical waterway to the establishment of a dedicated regulatory system, the Pinglu Canal is creating more than a new maritime corridor for southwestern China. It is building a foundation for closer coordination among infrastructure, industrial development, logistics services and navigation governance. As operations mature, cargo flows stabilize and industries cluster along the route, the canal has the potential to become a vital link between China’s southwestern hinterland and international markets, providing fresh momentum for the development of the New International Land–Sea Trade Corridor and more balanced regional growth.

Source: 21jingji, CGTN, xinhua, cctv, people

From AI Toys to 15 Billion Tokens a Day: How China’s Shantou Is Building a New Digital Toy Export Economy

0

In September 2026, a young girl in a Southeast Asian household was chatting with her new AI teddy bear. The toy understood her instructions and responded almost instantly, turning an ordinary playtime into an interactive experience. Thousands of kilometres away in Shantou, Guangdong Province, computing infrastructure was working continuously behind the scenes. Large AI models processed the girl’s requests and generated responses, which were then transmitted back to the overseas device through international telecommunications networks.

The teddy bear and the computing power behind it had travelled abroad in very different ways. The physical toy had left the production lines of Chenghai, Shantou’s renowned toy manufacturing hub, and crossed borders through conventional logistics. The digital intelligence that brought it to life, however, continued to be delivered from data centres in Shantou with every question, response and interaction.

The two exports, manufactured goods and digital services, are increasingly becoming part of the same industrial value chain. For Shantou, a city with decades of manufacturing and international trade experience, the convergence of artificial intelligence and computing services is opening a new chapter in its economic transformation.

Chenghai is one of the world’s major toy manufacturing centres, producing approximately one-third of the world’s plastic toys. Over the years, the district has developed a comprehensive industrial ecosystem spanning product design, mould-making, injection moulding, assembly and supply-chain management. Yet, like many traditional manufacturing clusters, its toy industry has long faced pressure from product homogenisation, limited brand premiums and narrowing profit margins. Competing primarily on production scale and cost has become increasingly difficult as manufacturers seek sustainable growth.

Artificial intelligence offers a potential way forward, but integrating AI into traditional toys requires more than adding a microphone or speaker. Manufacturers must also address model integration, communications, computing resources, software development and data compliance. For small and medium-sized enterprises, building an entire AI technology stack independently can involve substantial investment, lengthy development cycles and ongoing maintenance costs.

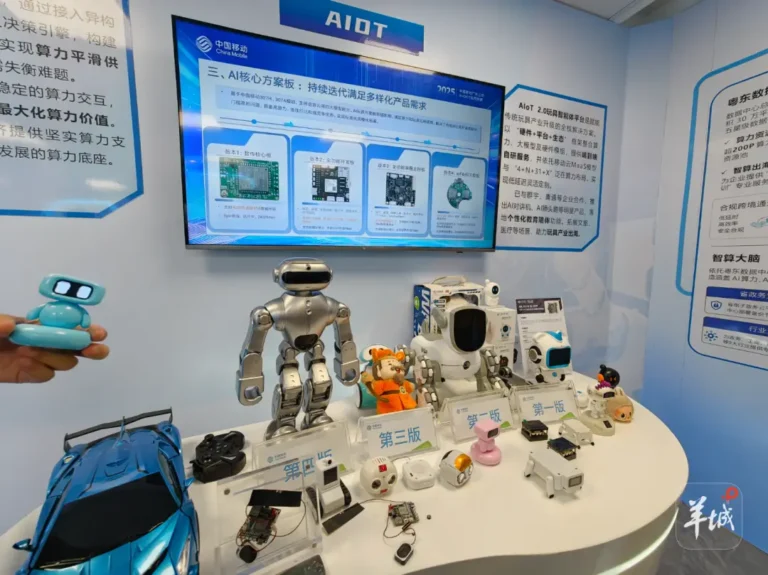
To lower these barriers, China Mobile’s Shantou branch has developed an integrated service system that combines connectivity, computing power and AI capabilities. In 2025, the company introduced an AI toy solution board and launched an AIoT toy agent platform, providing standardised modules, solution boards, communication chips and platform services that can be integrated into existing manufacturing processes. Instead of developing every component from scratch, manufacturers can select the capabilities they need and incorporate them into their products.

According to relevant estimates, some manufacturers can bring AI toys into mass production in as little as three weeks. The platform-based approach can shorten AI transformation cycles by approximately 60% and save around RMB 200,000 in upgrade costs. China Mobile previously reported that nearly 200,000 AI toy modules had been signed up for deployment, with services reaching more than 100 local toy companies. These developments are helping AI move beyond a small number of technology-intensive businesses and into the broader manufacturing ecosystem.

A further milestone came on March 23, 2026, when the Shantou AI Toy Industry Ecosystem Conference was held at the Shantou Cross-Border Digital Economy Industrial Park. China Mobile’s Shantou branch unveiled its first OpenClaw intelligent toy, alongside a series of products and services, including the AIoT 2.0 integrated platform, the Suanli Tongyi Token platform, AI-SIM cards and AIoT solution boards.

The launch marked a shift from technical solutions and component supply towards tangible products and commercial-scale manufacturing. Cooperation across the semiconductor, hardware, large-model, computing, cross-border e-commerce and overseas telecommunications sectors is also helping establish a more complete support system for companies seeking to develop and export AI toys.

The significance of this ecosystem extends beyond giving toys new features. By combining standardised hardware, intelligent-agent platforms and computing services, it allows smaller manufacturers to develop products with lower upfront investment and greater flexibility. Companies can adapt language capabilities, interactive functions and content to different overseas markets without having to build their own AI infrastructure. Traditional toy manufacturers are gaining access to the AI value chain, while technology providers are finding scalable applications for their services.

As AI toys reach international markets, another opportunity is emerging: the export of computing services themselves.

For an AI-enabled toy, the initial hardware sale is only the beginning of its commercial life. Everyday conversations, content updates, remote software upgrades and personalised services all require ongoing access to AI models. Revenue opportunities can therefore extend beyond a one-off product transaction to include long-term operations and recurring digital services.

However, manufacturers have faced two major obstacles: the cost of accessing overseas AI models and the complexity of cross-border data compliance. Some companies previously relied on overseas models such as ChatGPT, where service costs could be significantly higher than those of comparable domestic solutions. At the same time, different jurisdictions impose different requirements on personal information, voice data and cross-border data transfers. Individual toy manufacturers often lack the resources to manage these technical and regulatory challenges independently.

Shantou’s emerging Token export model is designed to address these constraints. In April 2026, the city completed what was reported as China’s first full-chain verification of Token exports, establishing a closed-loop process for delivering AI inference services to overseas users.

Under this model, an overseas user submits a request to an AI application. The request enters a designated service zone through a compliant connection, where a data centre in Shantou performs model inference and processes the associated tokens. The result is then transmitted back to the overseas device through international telecommunications networks. The computing and token consumption take place in China, while the resulting AI service is delivered to users abroad.

A token is a basic unit used by large language models to process and generate information. Every prompt and response may consume a certain number of tokens. For AI toys, tokens underpin the ability to understand instructions, formulate language and generate interactive responses. For computing service providers, token consumption also offers a way to measure usage, calculate service costs and explore revenue-sharing arrangements across the AI ecosystem.

Shantou’s ability to develop this model rests on several complementary advantages. Its international submarine cable landing infrastructure and telecommunications networks provide connectivity to overseas markets. Deploying computing resources locally can reduce reliance on overseas service intermediaries, while optimising model access can help control latency and costs. The city’s participation in the “data processing and service export” pilot in the Shantou Overseas Chinese Economic and Cultural Cooperation Pilot Zone also provides a framework for exploring compliant data processing and cross-border service delivery, subject to applicable regulations.

According to reported cases, an individual AI toy interaction can cost approximately RMB 0.03, with a response time of around 900 milliseconds. Related deployments have reduced the latency between the two locations to 32.7 milliseconds, while certain computing services cost more than 30% less than overseas alternatives. As adoption has expanded, the volume of exported tokens has risen sharply, from an average of approximately 100 million per day at the end of April 2026 to a daily level in the tens of billions.

By September 2026, Shantou was supplying more than 15 billion tokens a day to overseas markets, according to local industry reporting. The services supported a growing range of applications, including AI toys, cross-border e-commerce, digital-human customer service, AI-generated short dramas and overseas marketing content.

For toy manufacturers, these developments are changing the economics of their products. Traditionally, the value of a toy has been concentrated in materials, design, manufacturing and distribution. Once AI capabilities are introduced, product competitiveness also depends on the quality of interaction, model performance, content updates and long-term service delivery.

A conventional plastic toy can potentially command a price of several hundred yuan after being upgraded into an interactive AI product, compared with a price of only a few dozen yuan for a basic version. At the same time, access to domestic models and locally deployed computing resources can reduce ongoing operating costs. Lower service costs and higher product value create new opportunities for manufacturers competing in overseas markets.

The transformation is also reshaping Shantou’s cross-border e-commerce sector. A growing number of young entrepreneurs are applying AI to overseas product selection, customer enquiries, marketing content generation and order management. For these businesses, AI is not merely a feature embedded in a toy; it is also a tool for connecting suppliers, sales channels and international consumers.

Entrepreneurs such as Luo Rui, who works in global product sourcing and cross-border commerce in Shantou, see AI as an opportunity to expand the services offered to traditional manufacturers. With intelligent agents handling routine tasks, relatively small teams can manage workloads that previously required considerably more personnel. The combination of manufacturing expertise, established foreign-trade networks and AI-powered operations is creating new forms of cooperation across the local economy.

A more comprehensive industrial ecosystem is helping support this transition. At the March 2026 industry conference, China Mobile’s Shantou branch signed a strategic cooperation framework agreement on AI toy ecosystem development with the Shantou Overseas Chinese Economic and Cultural Cooperation Pilot Zone, the Chenghai District People’s Government, the Shantou Chenghai Toy Association and the Shenzhen Artificial Intelligence Association. The company also established deeper industrial partnerships with local intelligent-hardware businesses covering solution development, module production and mass manufacturing.

The Shantou AI Toy Innovation Centre was unveiled at the same event. Designed to support research and development, manufacturing, business incubation and overseas expansion, the centre is intended to bring together resources that have traditionally been spread across different parts of the industrial chain.

The Suanli Tongyi Token platform is another important component of this ecosystem. By integrating multiple AI models and computing resources, it provides businesses with centralised access, intelligent computing-resource allocation and billing services. It also offers a framework for coordinating service providers and exploring how value can be distributed among ecosystem participants.

For manufacturers, this integrated approach can reduce the need to negotiate separately with multiple technology suppliers. For computing providers and software developers, it creates opportunities to reach a wider range of applications and improve resource utilisation. In this sense, the platform is intended to function not simply as a technical tool but as a link between computing infrastructure, AI developers and manufacturing businesses.

As demand grows, expanding computing capacity and strengthening service capabilities will become increasingly important. Local plans include increasing the capacity of the eastern Guangdong data-centre cluster, improving multilingual model support and developing cross-border compliance systems. Shantou is also exploring the extension of its Token export capabilities into cross-border e-commerce, gaming, digital content and AI-generated animation, linking computing services with additional sectors that already possess international market experience.

Nevertheless, the Token export model remains at an early stage, and its expansion faces significant challenges. Current applications are concentrated largely in AI toys, with Southeast Asia serving as a major target market. Different countries and regions have distinct requirements concerning data localisation, personal information protection and AI services. Some markets impose strict restrictions on cross-border data transfers and related technology services, potentially limiting the range of business models available.

Other challenges include multilingual adaptation, local customer support, service reliability and the continuing cost of regulatory compliance. Expanding infrastructure alone will not guarantee sustainable growth. Shantou will also need to strengthen technical standards, improve operational services and deepen cooperation with overseas partners if it is to turn its early progress into a lasting competitive advantage.

The city’s current transformation builds on an industrial history stretching back to the early years of China’s reform and opening-up. Supported by its overseas Chinese networks and foreign-trade connections, Shantou developed a strong manufacturing base in toys, textiles and garments. The “front shop, back factory” model helped establish production capacity, international business relationships and extensive export experience.

Artificial intelligence is now introducing new technological elements into that established industrial system. Toys continue to leave factories in Chenghai, but their value is no longer limited to plastic components, moulds and assembly. A digital link connecting local computing resources with global users gives manufacturers an opportunity to participate in model services, content operations and digital trade.

From bringing AI toys into mass production in as little as three weeks to supplying more than 15 billion tokens a day to overseas markets, Shantou is exploring a development path in which manufacturing and digital services reinforce one another. The underlying transformation is not simply about adding AI features to conventional products. It is about connecting hardware production, model capabilities, computing services and cross-border operations into a more integrated value chain.

As an AI toy enters an overseas household, every subsequent interaction may generate demand for another digital service. For Shantou, the longer-term opportunity lies not only in exporting more intelligent toys, but also in moving beyond one-time product sales towards a model in which manufactured goods and recurring digital services are delivered together to global markets.

Source: stcn, 21jingji, xinhua, stdaily, chinanews, sohu

A Billion-Dollar Food Empire: How A Small Chinese County Is Betting on Pigs to Transform Its Economy

0

In Qinggang County, Heilongjiang Province, a pig is undergoing a transformation from a conventional agricultural product into the centerpiece of a modern food industry.

From corn cultivation and feed production to breeding, hog farming, slaughtering, food processing, cold-chain logistics and retail, Qinggang is bringing together what were once separate stages of the pork supply chain within a single county. The county now aims to develop the sector into a roughly $1.4 billion industry within three to five years.

The ambition is not built on a blank slate. Qinggang is a major grain-producing and hog-producing county. Annual grain output is about 1.15 billion kilograms, while the county’s hog inventory has traditionally remained above one million head. Its abundant corn production provides a natural foundation for feed manufacturing and livestock farming. The more decisive change, however, has come from the county’s long-term partnership with Sichuan-based agricultural and food company Tieqili Group.

Tieqili entered Qinggang in 2017. The following year, the company and the county government signed a strategic cooperation agreement covering a million-head hog industry. Qinggang subsequently invested about $90 million, to build a parent-stock breeding farm, a grandparent breeding facility and a series of finishing farms. Together, these facilities have established a more standardized and industrialized breeding system. The group has also developed feed production in the county. A modern feed plant launched in 2021 has a designed annual capacity of 200,000 tons, while the group’s total feed capacity in Northeast China has reached 400,000 tons.

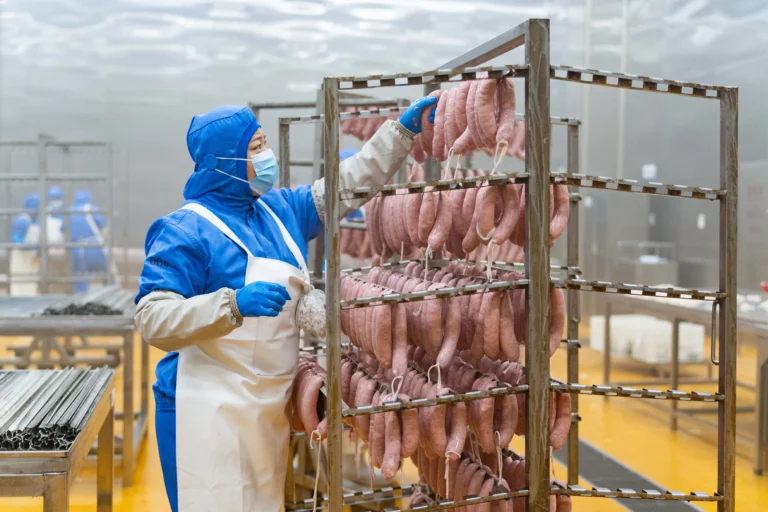
The other major pillar of the chain is Heilongjiang Maple Ranch Food Co., Ltd. The company invested about $34 million, in its Qinggang operation, which began production in 2023. Its modern slaughtering facility has an annual capacity of two million hogs. Inspection, testing, carcass processing, cooling and aging are integrated into a standardized production system, with food-safety data incorporated into a traceability platform. Feed batches, farms and processing information can be traced through the production chain.

The biggest economic shift, however, comes after slaughtering. In the past, a hog leaving the farm generally meant that much of its potential added value was created elsewhere. Qinggang is now trying to capture that value locally by turning pork into sausages, cured meats, cooked products and other processed foods. The county has developed an annual processed-food capacity of about 30,000 tons, with more than 100 product varieties. In 2025, Maple Ranch slaughtered 406,400 hogs and processed 51,300 tons of fresh and prepared meat products, generating revenue of $108 million.

The result is more than a conventional hog-farming operation. It is an integrated industrial chain in which grain provides the raw material, feed connects crop production with livestock, breeding and farming form the agricultural core, slaughtering and processing create additional value, and logistics and retail extend the chain to consumers. The longer the chain remains within the county, the greater the potential for local output, employment, tax revenue and supporting services.

A distinctive feature of the Qinggang model is how the economic benefits of the industrial chain are distributed. Under its government-business cooperation framework, agricultural assets financed by the county government are operated by Tieqili. The projects generate guaranteed annual returns of more than $4.2 million. These returns are incorporated into village-level collective income programs, with priority given to households with no labor capacity and formerly impoverished residents.

The approach forms part of Qinggang’s broader “2+N” mechanism for linking industry with rural incomes, centered on two major county industries, hog farming and photovoltaic power. The county has invested approximately $2.7 billion, in related support assets and programs. In 2025, operating assets generated around $11.8 million, in income, benefiting more than 31,000 people.

The underlying idea is not to transfer farming and market risks to individual households, but to use industrial assets, employment and collective income mechanisms to allow rural communities to share in the returns generated by industrial development.

Yet an integrated supply chain does not automatically translate into a highly competitive industrial cluster. Qinggang’s next challenge is to move from a complete industrial chain to a higher-value industrial chain.

The first challenge lies in farming. Large-scale standardized farms have improved production efficiency and biosecurity, but smaller producers still need stronger organization, technology and risk-management capabilities. Hog prices are inherently cyclical, and reliance on farming margins alone leaves producers vulnerable to market downturns. Expanding contract farming, strengthening agricultural insurance and improving price-risk management will therefore be critical to the sector’s resilience.

The second challenge is value creation. Slaughtering capacity by itself does not determine the competitiveness of a food industry. The greater value lies in brands, research and development, product innovation and distribution. Qinggang has moved beyond fresh pork into sausages, cured meats and cooked foods, but building nationally recognized brands, developing higher-margin products, making fuller use of slaughter by-products and establishing stronger e-commerce and retail channels remain important tasks.

This is where the planned Qinggang International Youfood Valley comes into play. Covering approximately 524 mu, or about 35 hectares, the industrial park involves planned investment of $63 million. Its infrastructure, standardized factory buildings and cold-storage facilities are being developed to attract food-processing, logistics, research and related businesses.

The objective is not simply to add factories, but to create an industrial ecosystem in which companies can share raw materials, technology, logistics, research capabilities and market channels. Qinggang plans to attract more than 10 large-scale enterprises within three to five years and turn the park into a food-processing cluster with annual output of $1.4 billion, while creating more than 3,000 jobs.

The county’s hog industry generated $261 million, in output in 2025, with Maple Ranch contributing $114.6 million. Reaching the $1.49 billion target would therefore require a substantial expansion beyond primary farming and slaughtering, particularly in processed foods, branding, logistics and the broader food-manufacturing ecosystem.

The significance of Qinggang’s experiment ultimately extends beyond whether it reaches a particular output target. For an agricultural county, the fundamental challenge is how to convert grain production into food manufacturing, livestock production into processing value, and corporate investment into lasting employment and local economic activity.

Qinggang’s answer is to treat the pig not as the end product, but as the starting point of an industrial chain. When corn enters a feed mill, piglets enter standardized farms, hogs move into modern slaughtering facilities and pork emerges as sausages, cured meats and other branded foods, a traditional agricultural activity begins to function as a broader county-level industrial system.

Whether Qinggang can ultimately build a nationally competitive billion-dollar food cluster will depend on its ability to develop brands, attract complementary businesses, strengthen research and development, and expand its markets. But the county has already made a fundamental shift: turning a pig from a single agricultural commodity into the foundation of a much broader industrial economy.

Source: molihua, 21jingji, hlj gov cn, cfsn, sohu

70 Years On, China and Egypt Move from Historic Friendship to AI and Technology Cooperation

0

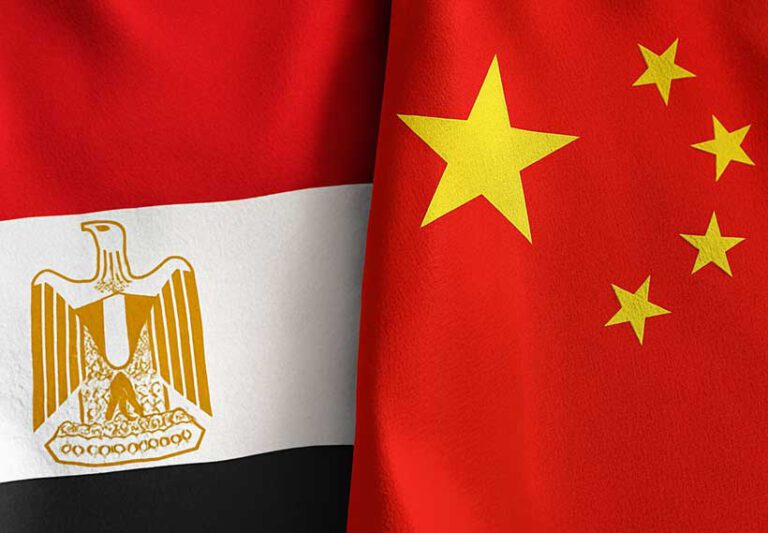
As the first Arab and African country to establish diplomatic relations with the People’s Republic of China, Egypt’s story with China has long gone beyond diplomatic rhetoric. At this important juncture, as the two countries look to build on the past while opening a new chapter, their partnership is gaining new possibilities. 

Zhao Jun, Associate Professor at the Institute of Middle East Studies at Shanghai International Studies University, has conducted extensive field research in Egypt and followed China-Egypt relations and China-Arab cooperation for many years. Zhao offers a systematic assessment from his own perspective, providing a grounded and pragmatic lens through which to understand the direction and prospects of China-Egypt relations in the new era.

2026 marks the 70th anniversary of diplomatic relations between China and Egypt, the first Arab and African country to establish diplomatic ties with the People’s Republic of China; how would you characterize the evolution of bilateral relations and their current historical position?

The evolution of China-Egypt relations over the past 70 years can broadly be divided into four stages: political consolidation from 1956 through the 1970s; institutionalized cooperation from the 1980s to the late 1990s; strategic and pragmatic expansion from 2000 to around 2013; and comprehensive strategic partnership since 2014.

Two dates are particularly significant. 1956 established the foundation of political trust, while 2014, when the two countries elevated their relationship to a comprehensive strategic partnership, marked a qualitative transformation. Over the past decade, cooperation has expanded from diplomacy and political support to infrastructure, industrial parks, energy, automobiles, digital economy and artificial intelligence.

The deeper transformation, however, lies in the changing nature of the relationship. It has moved from political solidarity to strategic cooperation and increasingly toward a broader vision of shared development and a community with a shared future. The TEDA Suez Economic and Trade Cooperation Zone and other major projects have translated political trust into industrial and economic cooperation.

Today, China-Egypt relations have acquired significance beyond the bilateral level. Egypt simultaneously belongs to the Arab, African, Middle Eastern, Mediterranean and Red Sea geopolitical spaces, while China is a major developing country and an important member of the Global South. Their cooperation therefore naturally intersects with China-Arab, China-Africa and broader Global South cooperation.

In this sense, the 70th anniversary should not be viewed merely as a commemorative milestone. It marks a transition from historical friendship toward a future-oriented partnership centered on modernization, Global South cooperation and a community with a shared future.

What have been the most significant achievements and structural constraints in the alignment of China’s and Egypt’s development strategies over the past decade?

The most significant achievement has been the transition from strategic convergence to project implementation and increasingly to industrial integration. Since the establishment of the comprehensive strategic partnership in 2014, the Belt and Road Initiative has been closely aligned with Egypt’s Vision 2030, producing projects such as the TEDA zone, the Central Business District in the New Administrative Capital, the Ramadan 10th of Ramadan railway and Egypt’s satellite program.

More importantly, cooperation is moving beyond construction and contracting toward localized manufacturing, supply chains and industrial capacity. Chinese investment in new energy, automobiles, home appliances, building materials and textiles is helping Egypt convert its geographic advantages around the Suez Canal into manufacturing and export capacity.

The experience suggests three important principles: strategic alignment provides long-term stability; industrial parks create clustering effects; and localization determines sustainability. The objective is not simply to transfer Chinese manufacturing capacity to Egypt, but to combine Chinese capital, technology and management with Egypt’s market, geography and resources to create mutually reinforcing industrial ecosystems.

The constraints have also changed. The central question is no longer whether there are projects, but whether those projects can generate sustainable economic returns. Egypt’s macroeconomic pressures, financing costs and foreign-exchange constraints have affected investment expectations. The next phase therefore requires deeper integration of trade, investment, industry, technology and human capital.

Can China’s zero-tariff policy for African countries significantly reshape the long-standing trade imbalance between China and Egypt?

The trade imbalance is a real issue, but it should not be reduced to a simple question of China exporting too much and Egypt exporting too little. The structure of trade matters as much as its aggregate value. A significant share of China’s exports to Egypt consists of intermediate goods that enter Egyptian manufacturing and can subsequently contribute to exports to third markets.

The zero-tariff policy creates an important institutional opportunity for Egypt to expand exports to the Chinese market, and the initial increase in Egyptian exports suggests that the policy is already producing effects. But tariffs are only one component of export competitiveness.

Whether the trade structure changes fundamentally will depend on Egypt’s ability to improve product quality, supply capacity, logistics, branding and knowledge of the Chinese market. Zero tariffs can accelerate export growth, but they cannot by themselves eliminate a structural trade deficit.

Ultimately, trade rebalancing requires industrial rebalancing. The key is to turn improved market access into durable industrial competitiveness.

As artificial intelligence, data centers and other emerging technologies enter the bilateral agenda, how should we understand the growing role of technology competition in China-Egypt relations?

Artificial intelligence is emerging as an important new area of China-Egypt cooperation, but its significance goes beyond individual commercial projects. AI chips, computing infrastructure, cloud services and data centers have strategic implications, placing technological cooperation within a broader environment of US-China technology competition.

It would nevertheless be misleading to portray Egypt simply as a “front line” of that competition. Egypt has traditionally pursued strategic autonomy and diversified external partnerships. Its primary objective is to secure technology, investment and digital capabilities from multiple sources rather than choose exclusively between China and the United States.

Egypt’s strategic significance derives from its population, geographic position and dual role in the Arab and African worlds. If it can use multiple sources of technology to build an open yet increasingly capable digital ecosystem, it could become an important node in the digital transformation of the Global South.

The real significance of China-Egypt AI cooperation therefore lies not in whether a particular data-center project is awarded to one company or another, but in whether the two sides can develop longer-term cooperation in joint research, talent development, industrial applications and digital governance, while addressing data sovereignty, cybersecurity and technological transparency.

How will Egypt’s strategic autonomy and balancing diplomacy affect China-Egypt relations amid intensifying regional polarization and major-power competition?

Egypt’s balancing diplomacy is essentially a form of strategic autonomy centered on national interests and the preservation of policy flexibility among competing powers. Rather than being a source of uncertainty for China-Egypt relations, this autonomy can provide an important foundation for their long-term development.

Egypt maintains relationships with China, the United States, Russia, Europe and the Gulf states. Its strategic value therefore lies not only in its domestic market but also in its ability to connect different regional and international networks.

China does not require an Egypt that is forced to choose sides; it benefits from an Egypt capable of making autonomous decisions and expanding its room for cooperation. As bilateral cooperation moves further into strategic sectors such as AI, digital infrastructure, renewable energy and advanced manufacturing, respecting Egypt’s foreign-policy autonomy will become increasingly important.

The likely trajectory is therefore not formal alignment, but overlapping interests, diversified partnerships and greater strategic coordination.

What does the deepening of China-Egypt military cooperation, including the “Eagles of Civilization” joint air exercises, mean for regional security?

China-Egypt military cooperation should be understood within the context of their long-standing strategic trust and Egypt’s tradition of maintaining diversified defense partnerships, rather than simply as evidence of geopolitical alignment.

The “Eagles of Civilization” exercises have evolved from personnel exchanges toward more systematic and increasingly realistic training, indicating deeper military confidence and operational cooperation. For China, this represents conventional defense cooperation; for Egypt, it provides an additional channel for enhancing military capabilities while preserving strategic flexibility.

Its regional significance lies primarily in the diversification of security cooperation rather than the formation of a new military bloc. Expanding cooperation into counterterrorism, maritime security, search and rescue, peacekeeping and disaster response could further strengthen its contribution to regional public security.

As Egypt increasingly serves as a link between China, the Middle East and Africa, how should its role as a “strategic hub” be distinguished from that of a traditional ally or partner?

I would describe Egypt more precisely as a strategically significant hub partner, rather than an agent or proxy. Egypt connects Africa and Asia and links the Red Sea, Mediterranean and Suez Canal, while simultaneously occupying important positions in both Arab and African affairs. This gives China-Egypt cooperation a naturally broad regional spillover effect.

Over the past decade, China has effectively developed a form of “hub-oriented” engagement with Egypt, extending bilateral cooperation toward China-Arab, China-Africa and third-party markets. This is less about geopolitical control than about using Egypt’s geographic and institutional position to connect different cooperation networks.

A strategic hub differs from an ally in that an alliance emphasizes security commitments and bloc politics; a partnership emphasizes equality and mutual benefit; a hub emphasizes connectivity and network value. Egypt does not need to choose between China and the United States for its position to have strategic significance.

What role does the China-Egypt relationship play in China’s broader engagement with the Arab League, and which elements of the bilateral experience are transferable to other Arab countries?

China-Egypt relations have significance for China-Arab cooperation in three respects: they demonstrate how political trust, development cooperation and cultural exchange can reinforce one another; Egypt provides an important institutional platform for China-Arab engagement; and bilateral strategic alignment offers mechanisms that can inform cooperation with other Arab states.

However, the Egyptian experience cannot simply be replicated. What can be transferred are mechanisms rather than models. Arab countries differ significantly in resource endowments, population size, industrial structures and development stages.

For Gulf states, cooperation may focus more heavily on energy transition, AI and finance; for other Arab countries, infrastructure, manufacturing and energy may be more relevant. The broader principles are therefore straightforward: mutual political respect, strategic alignment of development priorities and country-specific cooperation.

Source: guancha, moderndiplomacy

Building Offshore Finance in Shanghai: China’s Next Step in Financial Opening

0

China is a global trading and shipping powerhouse, yet its financial sector still accounts for a relatively limited share of high-value-added business worldwide. For years, large volumes of insurance, reinsurance, shipping finance, offshore trust and other international financial services have been dominated by Western institutions.

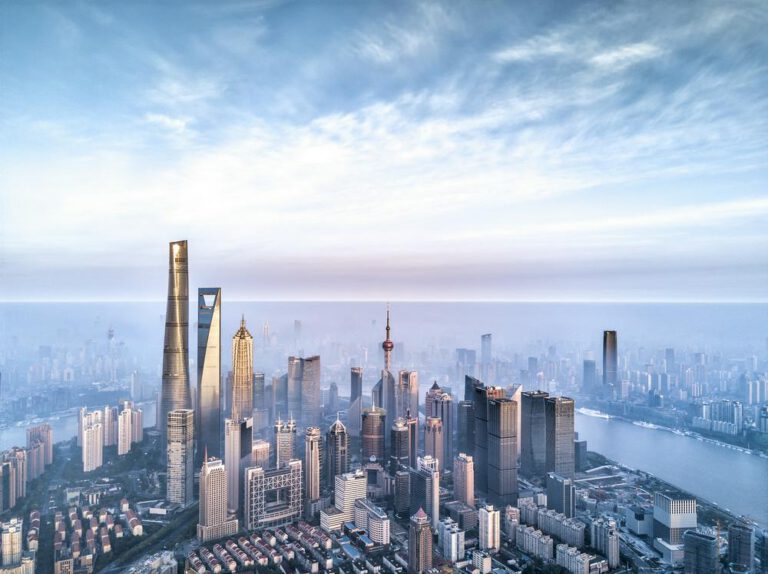
That landscape may now be entering a new phase. With the launch of the Action Plan for the Development of Offshore Finance in Shanghai International Financial Center, Shanghai is accelerating efforts to build an internationally competitive offshore financial system. 

Lian Ping, Chairman of the China Chief Economist Forum and President of the International Finance Institute, shares his views on the development of offshore finance in China, the strategic significance of Shanghai’s new offshore financial framework, and the opportunities and challenges it presents for China’s financial sector.

What is the strategic significance of offshore finance for China’s ambition to become a financial powerhouse and for Shanghai’s international financial center?

China is already deeply integrated into the global economy. As Chinese companies and financial institutions expand overseas, offshore finance can provide them with more efficient financial services, risk management and liquidity support. It can also serve foreign companies and economies that trade and invest with China.

More importantly, offshore finance offers China a relatively controllable channel for expanding financial openness. China has not yet reached the stage of completely liberalizing capital flows and currency convertibility. Offshore finance can therefore provide a higher degree of internationalization within a manageable regulatory framework. In that sense, it can become an important source of new momentum for Shanghai as an international financial center.

There is another particularly important dimension. Global offshore markets handle large volumes of high-value-added business, including trade finance, shipping finance, insurance and reinsurance. China has enormous trade and shipping volumes, yet Chinese financial institutions still capture only a limited share of the core financial services generated by these activities.

Developing offshore finance would give Chinese institutions a pathway into these global markets, strengthen their international competitiveness and allow China to capture more of the financial value generated by its own global economic activity.

How will Shanghai build its offshore financial system, and what are the key priorities and stages of implementation?

The framework can be summarized in three concepts: physical concentration, restricted participation and account segregation.

“Physical concentration” means initially concentrating offshore financial activities in Pudong. “Restricted participation” means that transactions will primarily involve non-residents. “Account segregation” requires offshore accounts to remain strictly separate from onshore accounts, ensuring that offshore funds and transactions are clearly distinguished. This is fundamental to risk management.

The Action Plan identifies six priority areas: offshore trade finance, free-trade offshore bonds, offshore reinsurance, treasury-center fund operations, offshore renminbi foreign-exchange trading, and financial services for non-resident individuals.

Implementation will proceed in three stages. By 2027, Shanghai aims to establish the basic rules, risk-management mechanisms and business environment for offshore finance. By 2030, it aims to develop a relatively mature institutional and legal framework. By 2035, the objective is to establish a strategic hub capable of coordinating onshore and offshore finance at a high level.

Offshore renminbi foreign-exchange trading has expanded rapidly since the pilot program began; what does that tell us about the market?

Rapid growth is common when a new market opens, and in this case it also indicates that there was substantial underlying demand that previously lacked an appropriate channel.

The renminbi has become increasingly internationalized, while Chinese commercial banks possess enormous renminbi and foreign-exchange positions. The participation of six major banks in the Shanghai Free Trade Zone therefore naturally generated a rapid increase in trading activity.

The more important indicators going forward will be market liquidity, the range of currencies traded, pricing capacity and the international composition of market participants. The pilot phase is currently dominated by Chinese banks. If more foreign financial institutions are allowed to participate, Shanghai could gradually develop into a genuinely global offshore foreign-exchange market.

What kind of tax framework does Shanghai need to make its offshore financial system internationally competitive?

Taxation is an important component of the competitiveness of any international financial center. Mature offshore centers generally do not simply apply their domestic tax regimes to offshore business. Instead, they develop arrangements tailored to international competition and specific business needs.

Shanghai should therefore avoid managing offshore finance entirely through an onshore tax framework. Offshore markets serve non-resident transactions and operate in an intensely competitive international environment. If the tax burden is significantly higher than that of comparable financial centers, business will naturally move elsewhere.

The appropriate approach is to consider international competitiveness and adopt differentiated policies. Certain strategically important businesses could receive appropriate tax incentives or exemptions, while regulatory mechanisms should simultaneously prevent tax arbitrage, foreign-exchange arbitrage and money laundering.

Across major Asian offshore centers, overall tax levels are broadly in the 12–16% range, although Shanghai should not simply copy any particular jurisdiction. The tax framework should reflect the nature of different businesses and the stage of market development.

Will Shanghai’s development of offshore finance compete with Hong Kong, or can the two centers complement each other?

Competition will inevitably exist, but the more important relationship is one of complementarity and market expansion. China is a very large economy, and as its trade, investment and overseas business continue to grow, the overall demand for offshore financial services will also expand.

Hong Kong is closely connected to the Greater Bay Area and the broader southern Chinese economy, while Shanghai is supported by the Yangtze River Delta, where advanced manufacturing, technology investment and emerging industries are developing rapidly. These different economic hinterlands generate distinct sources of financial demand.

Shanghai and Hong Kong can therefore develop differentiated strengths while competing constructively in global offshore markets. The objective should not simply be to redistribute an existing pool of business, but to expand China’s overall participation in international financial services.

What are the principal financial-sanctions risks China needs to prepare for?

The two most powerful financial-sanctions tools are restricting access to the SWIFT messaging system and freezing overseas assets. These measures have had significant effects on countries such as Iran and Russia.

For China, however, comprehensive financial sanctions would involve much greater costs and international spillovers. China is one of the world’s largest trading economies and an important participant in global finance. Any attempt to exclude China from SWIFT would disrupt a very large volume of international transactions, while alternative infrastructure such as the Cross-Border Interbank Payment System, or CIPS, would become increasingly important.

The more realistic concern is therefore targeted financial restrictions rather than comprehensive sanctions.

Asset freezes also raise fundamental questions about confidence in the international financial system. If assets can be arbitrarily frozen because of political disputes, confidence in the jurisdiction holding those assets is inevitably weakened. China therefore needs to strengthen cross-border payment infrastructure, diversify international asset allocation and enhance the resilience and autonomy of its financial system.

Does the recent increase in global central-bank gold purchases signal a long-term decline in confidence in the dollar, and where might the international monetary system be heading?

The rise in gold prices reflects inflation and geopolitical risks, but the deeper issue is uncertainty surrounding the international monetary system. Persistent U.S. fiscal deficits and rising debt, together with geopolitical tensions, have encouraged some countries to reassess their exposure to dollar assets.

That does not mean the dollar will quickly lose its dominant position. The United States still possesses deep financial markets, extensive international networks and significant institutional advantages. The dollar is unlikely to be displaced by another single currency in the short term.

Over a much longer horizon, however, the international monetary system could become more diversified. Several forms of monetary assets may coexist: sovereign currencies such as the dollar and renminbi; regional or group currencies such as the euro; international reserve assets such as the IMF’s Special Drawing Rights; and gold.

Gold is no longer a conventional currency, but it retains its function as a store of value and a hedge against systemic risk. Its renewed importance reflects broader uncertainty in the international monetary order.

From a 30-, 50- or even longer-term perspective, the global monetary system is undergoing structural change. The renminbi is likely to play a larger international role, but whether it can become one of the world’s principal reserve and international currencies will ultimately depend on a much broader set of factors, including the scale of China’s economy, the depth of its financial markets, technological capabilities and overall national strength.

Source: mindstream, guancha, cls, xinhua

America Cut Huawei Off From Google. Huawei Is Now Building Its Own Digital World

0

Bring a smartphone close to a home appliance, and the device can be discovered automatically, without downloading another app, creating another account, searching for the device or entering a Wi-Fi password. 

Measure blood pressure, blood glucose or body temperature, and data from different devices can be automatically consolidated into a health-management platform. In the kitchen, gas meters, alarms and shut-off valves that once operated independently can now work together across sensing, warning and control.

These are no longer futuristic concepts. They are emerging in real-world applications showcased at the 2026 HarmonyOS Ecosystem Conference. From smart homes and healthcare to gas utilities, transportation and industrial control, HarmonyOS and OpenHarmony are expanding into an increasingly broad range of business environments.

Beneath these seemingly unrelated applications lies a common shift: intelligence is moving beyond the upgrading of individual devices toward the coordination of multiple devices, the movement of data across systems, and the ability of AI to access and orchestrate capabilities distributed across different terminals.

This shift also signals a new stage in the digital transformation of industries. For years, the smart-device industry focused primarily on connectivity. Appliances, meters, sensors and industrial equipment were equipped with increasingly sophisticated functions, but they often operated within separate software ecosystems, communication protocols and data standards. Wi-Fi, Zigbee, Matter and PLC coexist with different operating environments such as RTOS, Linux and Android.

The result is a paradox familiar to both consumers and businesses: individual devices are becoming smarter, while the overall system remains fragmented. Consumers may need a different app for every appliance. Enterprises have to repeatedly adapt products to different operating systems and hardware platforms. Data collected by one device often remains trapped within that device or its proprietary platform.

The next challenge, therefore, is no longer simply whether devices can connect to the internet. It is whether they can understand one another, whether their data can move across systems, and whether AI can coordinate their capabilities. This is the problem HarmonyOS is increasingly attempting to address.

The smart home provides perhaps the clearest example. Haier has noted that a modern household may contain dozens or even hundreds of smart devices, running on different communication protocols and technical architectures. The difficult task is no longer getting an air conditioner, refrigerator or washing machine online individually. It is enabling these devices to work together around the needs of the household.

OpenHarmony provides an underlying framework for device discovery, connectivity and coordination. For consumers, this can mean fewer apps, fewer accounts and less complicated setup. For manufacturers, it creates the possibility of encapsulating the capabilities of different devices in a more standardized way. That change becomes even more significant when AI enters the picture.

An AI system operating in the physical world needs more than the ability to understand language or generate content. It needs to know what devices are available, what those devices can do, and how to safely invoke those capabilities. In other words, AI needs a pair of hands and feet.

This is where the role of an operating system begins to change. Traditionally, an operating system provided the basic environment in which applications and hardware interacted. In an AI-driven world, it increasingly needs to connect devices, data, computing resources and intelligent agents.

Gao Tongqing, chairman of the Global Intelligent IoT Consortium, has described operating systems as the underlying foundation of the digital world and AI as a core engine of industrial transformation. In his view, the two are moving beyond simple coexistence toward deeper integration.

The implication is significant. For AI to move from the cloud into homes, factories, hospitals, transportation systems and energy infrastructure, models alone are not enough. The underlying software must be able to coordinate devices, access data and manage distributed computing resources.

HarmonyOS’s multi-device architecture is designed around precisely this type of coordination. The value becomes particularly visible in industrial and public-service applications. In the gas sector, for example, a utility company may operate gas meters, alarms and valves supplied by different manufacturers. If each device requires separate integration, the system can quickly become a complicated web of one-to-one and one-to-many adaptations.

King Card Smart has been working with OpenHarmony on terminal adaptation, data security and distributed multi-device coordination. The objective is to connect measurement, sensing, warning and control into a more coherent operational chain. Healthcare presents a different version of the same problem.

Products showcased by Kefu Medical can collect data such as temperature, blood pressure and blood glucose from different devices and feed it into longer-term health management and AI analysis. Previously, measurements were often isolated events. Once data from different devices can be continuously aggregated, individual measurements become part of a longitudinal record.

The difference may appear small at the device level, but it is substantial at the system level.

The common thread running through these cases is not the creation of another “smart device.” It is the effort to make previously disconnected devices, data and services operate as a coordinated system.

That is also why HarmonyOS is increasingly moving beyond consumer electronics and into industrial digitalization. China’s digital industry generated more than RMB 20 trillion in revenue in the first half of 2026, according to figures cited at the conference, representing year-on-year growth of 13.6%. At the same time, the country’s “AI Plus” push is taking artificial intelligence into factories, homes, transportation networks, energy systems and healthcare.

As the number of intelligent terminals grows, the importance of the underlying software architecture grows with it. Transportation offers a clear example. Jiaotong Jiahong, developed by JiaDu Technology, is designed to connect different station systems through a unified operating-system framework. Shenzhen’s Honglingnan Station has become a pilot smart station based on HarmonyOS technology.

Elsewhere, Shenkaihong and Shenzhen Expressway have developed a smart-highway solution based on OpenHarmony and RISC-V, covering areas such as road-condition monitoring, equipment maintenance and traffic management. In Zhejiang’s Pujiang County, more than 1,600 streetlights along the G351 road have been upgraded with OpenHarmony technology, enabling dynamic lighting based on approaching vehicles.

Industrial control represents another important application. Industrial operating systems based on OpenHarmony are being used to connect controllers and equipment from different manufacturers, with the goal of improving interoperability and enabling more integrated industrial data flows.

Healthcare is similarly moving toward coordinated environments. At Nanshan Hospital in Shenzhen, a HarmonyOS-based smart ward integrates mobile nursing carts, millimeter-wave radar, smart mattresses and infusion-monitoring equipment. Patient vital signs can be automatically synchronized with nursing systems, while sensors can assist in detecting risks such as falls.

The significance of these projects goes beyond the performance of any individual device.

Early digital-transformation projects were often built around individual customers or locations: one hospital developed one system, one factory deployed another, and one railway station built a separate platform. Such projects could be successful but were difficult to reproduce at scale.

The deeper promise of an operating-system ecosystem is standardization. Once interfaces, development frameworks and certification processes become standardized, a solution developed for one environment can potentially be adapted to many others. Digital transformation begins to move from project-by-project customization toward repeatable products and platforms.

OpenHarmony has now developed into a broad ecosystem. According to figures released at the conference, the OpenHarmony community has more than 13,000 contributors, over 650 ecosystem partners and more than 2,000 ecosystem products. More than 100 industry-specific distributions, including versions serving electricity, industrial applications and mobile scenarios, have emerged, covering areas such as finance, manufacturing, transportation, healthcare, energy and government services.

The industry is also attempting to strengthen standardization. GIIC has previously released 11 standards covering areas such as interoperability and SDKs, with nearly 30 additional standards planned for 2026. The “Hongtu Plan” announced at this year’s conference aims to extend ecosystem support across development, testing and commercialization. A unified certification mechanism is expected to cover OpenHarmony compatibility, unified interoperability and HarmonyOS Connect scenarios, with the stated goal of reducing testing time and costs.

The underlying objective is straightforward: move from having products to having products that can be commercially deployed at scale. That distinction matters. An operating system does not become an industrial platform simply because it has a large number of compatible devices. It needs developers, applications, manufacturers, users and commercial incentives to reinforce one another. HarmonyOS is approaching an important milestone on that front.

As of August 20, 2026, more than 80 million devices had been upgraded to HarmonyOS 6, with the company expecting the figure to exceed 100 million in the fourth quarter. Native HarmonyOS applications have surpassed 100,000, while more than 400,000 applications are available on HarmonyOS smartphones.

The OpenHarmony ecosystem, meanwhile, is reported to encompass more than 1.35 billion devices, with more than 13,000 registered community contributors and over 2,040 products having passed compatibility certification. Huawei rotating chairman Xu Zhijun has described the 100-million-user milestone as a form of “critical mass.” The analogy points to an important economic mechanism: once an ecosystem reaches sufficient scale, developers have stronger incentives to invest, users gain access to more applications and devices, and manufacturers have greater reasons to support the platform.

The ecosystem can begin to reinforce itself rather than relying primarily on individual companies or demonstration projects. Shenzhen has become an important testing ground for this model. The city has hosted the HarmonyOS Ecosystem Conference for three consecutive years, reflecting its unusually complete industrial chain, spanning chips, modules, operating-system development, hardware manufacturing and application services.

More importantly, local governments have opened real-world environments to technology developers. Smart-city projects, industrial parks and public services provide conditions in which operating systems can be tested under far more complicated circumstances than those found in laboratories.

Local policy initiatives have also helped accelerate ecosystem development. Longgang District, for example, has introduced a package of policies supporting HarmonyOS-related projects and established a number of demonstration scenarios and industrial parks. Longhua and Luohu have also developed innovation centers and training programs around the OpenHarmony ecosystem.

For an operating system, these real-world environments are crucial. Compatibility, security and reliability are ultimately determined not by demonstrations but by whether a system can operate continuously across complex hospitals, factories, transportation networks and public infrastructure.

Yet the next stage will bring a different set of challenges. Xu Zhijun has acknowledged that while HarmonyOS has established a foothold in China, its longer-term development still depends on two major questions: how effectively it can capture the opportunities created by AI, and whether it can expand internationally. These challenges point to two distinct dimensions of competition.

The first is technological. The future operating-system race may be less about the number of apps available on a device and more about how effectively the system can understand the physical world, coordinate hardware capabilities and support AI agents.

As AI moves from screens into physical environments, the operating system could become the layer that translates AI’s intentions into actions performed by devices. The second challenge is ecosystem globalization. A platform that seeks to become a global infrastructure layer must operate across different technical standards, developer communities, supply chains, regulatory environments and consumer markets. Domestic scale can provide a strong foundation, but it does not automatically translate into global adoption.

This makes the current stage of HarmonyOS particularly important. The platform has moved beyond the initial question of whether an alternative ecosystem can be built. The more consequential question is whether that ecosystem can become sufficiently standardized, commercially viable and technically capable to support large-scale deployment across industries.

The evolution from connectivity to intelligence is not simply a matter of adding more functions to more devices. “Connected” devices can exchange signals. “Intelligent” systems need to understand context, coordinate capabilities and make decisions. That distinction is becoming increasingly important as AI enters the physical economy.

The first era of the smart-device industry was largely about making individual products intelligent. The next era is likely to be about making systems intelligent. In that transition, the operating system is moving from an invisible layer beneath the device to a potential infrastructure layer connecting hardware, data, applications and AI.

For industries undergoing digital transformation, the question is therefore changing as well. It is no longer simply whether to adopt AI, but how AI can be brought into real business environments and given secure, standardized and scalable access to the devices and data that those businesses depend on.

HarmonyOS is positioning itself around that transition. Whether it can turn technological capabilities into widely adopted standards, standards into commercial products, and products into a self-sustaining global ecosystem will determine how far the platform can ultimately go. 

The shift from the Internet of Things to an intelligent Internet of Things is only beginning. And in that transition, the battle is increasingly moving away from individual devices toward the underlying systems that allow millions of devices to work as one.

Source: sznews, china daily, eastmoney, giiconsortium, huawei

A Small Town in Guangdong Commands the World’s Largest Share of the Electronic Aluminum Foil Market

0

In the race to build ever more powerful artificial intelligence infrastructure, some of the most important components are far removed from the headlines. They are not GPUs, servers or data centers, but materials measured in fractions of a millimeter. Among them is aluminum foil, in some applications as thin as 0.02 millimeters.

As AI servers become increasingly powerful, their power density is rising rapidly, placing greater demands on power management, heat dissipation and system reliability. Aluminum foil sits at the heart of several of these systems. It is used in thermal-management applications, while high-end electronic aluminum foil is also a critical raw material for the electrode foils used in aluminum electrolytic capacitors, which help stabilize power systems.

The expansion of AI computing is therefore beginning to reshape demand deep inside the materials supply chain. According to a research report by BOC International Securities, the global market for electrode foil used in aluminum electrolytic capacitors for AI servers is expected to reach RMB 2.59 billion in 2026 and RMB 5.02 billion in 2027, potentially exceeding RMB 10 billion by 2029.

The numbers point to a broader shift. The competition for AI computing power is no longer confined to chips and servers. Increasingly, it is also a competition over materials, energy, manufacturing processes and supply-chain resilience. At the upstream end of that chain, a mountainous county in southern China is emerging as an unlikely industrial hub.

Ruyuan Yao Autonomous County, in China’s Guangdong Province’s Shaoguan City, does not produce aluminum. Yet after more than two decades of industrial development, it has built one of the world’s largest clusters for electronic aluminum foil and related products. In 2025, the county’s aluminum-foil industry generated RMB 12.132 billion in output. Its electronic aluminum foil and medium- and high-voltage corrosion foil products have established leading positions in global markets, with core products accounting for more than 22 percent of global market share.

At the center of this industrial ecosystem is Dongyangguang, an aluminum and advanced-materials group that has gradually built a vertically integrated chain spanning electronic foil, corrosion foil, formed foil and aluminum electrolytic capacitors.

The story of Ruyuan’s aluminum-foil industry did not begin with aluminum. It began with a decision to locate a technologically demanding manufacturing business in a place that, on the surface, appeared to have few natural advantages for it.

In 1997, entrepreneur Zhang Zhongneng, originally from Dongyang in Zhejiang Province, began investing in Ruyuan. The following year, Dongyangguang established its first formed-foil plant there.

The choice was less unusual than it initially appeared. Formed foil is a core material for aluminum electrolytic capacitors, whose major customers were concentrated in the Pearl River Delta. Ruyuan was relatively close to this enormous manufacturing market. At the same time, the county had abundant hydropower resources, an important advantage for an electricity-intensive manufacturing process.

Ruyuan therefore offered something more valuable than access to aluminum itself: a combination of energy, cost and proximity to customers.

But these advantages alone could not have created a global industrial cluster. Technology was the decisive factor.

When Dongyangguang entered the field, key technologies for electronic foil production were dominated by Japanese companies. Working with universities and research institutions, the company developed new corrosion processes and eventually raised material yields to above 98 percent, helping to replace imported products and establish a domestic manufacturing base.

That breakthrough became the starting point for a much broader industrial strategy.

Rather than remaining focused on one product, Dongyangguang expanded along adjacent links of the value chain. It moved from formed foil into corrosion foil, then upstream into electronic bright foil, while also extending downstream into aluminum electrolytic capacitors. Over time, the company developed an integrated chain covering electronic bright foil, corrosion foil, formed foil and capacitors.

The logic was not simply vertical integration for its own sake. Each new business was connected to an existing technological capability, customer relationship or manufacturing process. This “chain-based” model also drove Dongyangguang beyond the capacitor-materials business. The company expanded into air-conditioning foil, automotive thermal-management materials and aluminum foil for new-energy batteries.

In 2010, Dongyangguang established a joint venture in Ruyuan focused on high-performance aluminum foil. As the automotive industry pursued lighter vehicles without sacrificing thermal performance, the company developed high-performance air-conditioning foil and brazing foil. Its MB fin technology, for example, was designed to reduce the weight of automotive heat exchangers while maintaining heat-transfer performance.

The rise of electric vehicles created another opportunity. Aluminum foil is used as a current collector in lithium-ion batteries, providing a conductive framework inside the cell. Dongyangguang subsequently entered the battery-foil market, and its Ruyuan facility now has an annual battery aluminum-foil capacity of around 12,000 tonnes. The company’s industrial expansion did not stop at aluminum.

The corrosion and forming processes used in electronic foil manufacturing require significant quantities of chemical inputs. To secure its raw-material supply, Dongyangguang built chlor-alkali production facilities and subsequently expanded into chloromethanes, fluorochemicals and PVDF, a high-performance polymer widely used in lithium batteries and photovoltaic applications.

The result is a broader industrial ecosystem in which aluminum materials, chemicals, energy and electronic components reinforce one another. This is what distinguishes Ruyuan from a conventional manufacturing base. Its competitive advantage is no longer a single factory or a single product, but an interconnected industrial system.

Over more than two decades, Dongyangguang has invested more than RMB 20 billion in Ruyuan. Other companies have gradually been attracted to the area, filling gaps around the anchor enterprise. The county has developed a supply chain stretching from aluminum ingots and electronic bright foil to corrosion foil, formed foil and capacitors, while also branching into chemical and new-energy materials.

Local government has played a supporting role by targeting investment around the leading enterprise and focusing on filling specific gaps in the supply chain. The objective is to transform an individual corporate success into a broader industrial cluster.

That industrial architecture is now encountering a new source of demand: AI computing.

The most visible components of an AI server are processors and accelerators. But keeping those processors running reliably requires a complex power and thermal-management infrastructure. As server power density increases, capacitors must deliver higher capacitance and voltage performance while occupying less space and maintaining high reliability.

That shift directly benefits high-end electronic aluminum foil and electrode-foil manufacturers. Dongyangguang’s recent results illustrate the change. In the first half of 2026, its high-end aluminum-foil business generated RMB 3.673 billion in revenue, up 26.35 percent year on year. Revenue from its electronic components and materials business reached RMB 1.902 billion.

The company’s AI-related business is growing from a much smaller base but at a much faster rate. In the first half of 2026, AI-related revenue reached RMB 289 million, an increase of more than elevenfold year on year. The company’s AI portfolio includes computing services as well as components and technologies linked to power and thermal management.

The more important development, however, may be occurring inside the materials business itself.

Dongyangguang is pushing into higher-performance products with greater capacitance, higher voltage tolerance and improved reliability. Its laminated-foil technology, developed through long-term cooperation with Japanese partner Toyo Aluminium, uses an additive forming process rather than conventional chemical corrosion. According to the company, the technology can increase capacitance per unit area by 20 to 40 percent compared with conventional corrosion foil, potentially allowing capacitors to become 20 to 30 percent smaller at the same capacitance.

For AI servers, such improvements are more than incremental material upgrades. They address one of the central engineering challenges of modern computing infrastructure: delivering more electrical performance within increasingly constrained physical space.

Market demand is already pushing manufacturers to upgrade their production lines. High-end medium- and high-voltage corrosion foil has seen particularly strong orders, while Dongyangguang has accelerated both production-line upgrades and new capacity construction in Ruyuan.

The significance of this expansion lies not simply in producing more aluminum foil. The competitive frontier is shifting from capacity to high-end capacity. That distinction will determine whether Ruyuan can sustain its position in the next stage of industrial development. The first phase of the county’s growth was about moving from zero to one: establishing a manufacturing base, mastering core technologies and building a complete supply chain. The next phase is likely to be about moving from scale to sophistication.

High-end electronic aluminum foil is an industry with substantial technical and certification barriers. Increasing output alone does not guarantee competitiveness. Manufacturers must control aluminum purity, grain structure, corrosion behavior, forming processes, product consistency and yield rates at increasingly demanding levels.

Ruyuan’s investment in research and digital manufacturing is therefore becoming as important as its physical production capacity. Cluster companies reportedly allocate more than 3 percent of revenue to research and development, while Dongyangguang has established postdoctoral and engineering research platforms. Its manufacturing operations have also adopted digital systems such as MES and ERP to monitor production processes and improve consistency.

Sustainability is emerging as another competitive variable.Aluminum processing and chemical manufacturing are energy- and resource-intensive businesses. Ruyuan’s historic advantage in hydropower can increasingly be viewed through a different lens: as a foundation for lower-carbon manufacturing. As data-center operators and technology companies place greater emphasis on renewable energy and supply-chain emissions, the environmental profile of materials may become an increasingly important part of their competitiveness.

Ruyuan also benefits from something beyond its own industrial capabilities: its location within Shaoguan’s emerging computing infrastructure. In 2022, Shaoguan was designated as the location of the Guangdong-Hong Kong-Macao Greater Bay Area national hub node’s data-center cluster under China’s national integrated computing-power network. The policy was intended in part to develop computing infrastructure outside the core cities of the Greater Bay Area while providing large-scale computing capacity to markets such as Guangzhou and Shenzhen.

This creates a potentially important connection between Ruyuan’s manufacturing economy and the regional computing economy. The opportunity is not simply to supply one material to one server. A more ambitious model would connect advanced materials with data centers, power equipment, liquid cooling, energy storage and electronic components, creating a broader regional ecosystem around computing infrastructure.

For Ruyuan, this distinction matters. The real question is not whether aluminum foil can “catch the AI wave.” Demand cycles come and go, and individual applications can change rapidly. The more fundamental question is whether AI can become a catalyst for upgrading an already established manufacturing ecosystem.

The conditions are increasingly visible. Ruyuan has accumulated manufacturing expertise, technological capabilities, a mature supply chain and an anchor enterprise with global customers. Shaoguan provides a growing computing-infrastructure market. AI, meanwhile, is raising the technical requirements for power electronics and thermal management.

Together, these forces could push the county’s industrial cluster into a new phase. The transformation also illustrates a broader possibility for China’s county-level manufacturing economy. A region does not necessarily need mines, oil fields or other natural-resource endowments to become globally competitive in advanced materials. What matters can be the ability to combine energy, infrastructure, technology, customers and industrial organization over a sufficiently long period.

More than two decades ago, Ruyuan attracted an aluminum-foil manufacturer because it offered cheap and reliable electricity and access to the Pearl River Delta market. Technology then turned that initial advantage into a foothold in a highly specialized industry. Supply-chain integration transformed the foothold into an industrial cluster. And now, the expansion of AI computing is creating a new layer of demand.

A sheet of aluminum foil may be only 0.02 millimeters thick, but the industrial system behind it is anything but thin. In Ruyuan, the next stage of competition will not be determined by how much aluminum foil can be produced. It will be determined by how far the cluster can move up the value chain, from volume to precision, from manufacturing to innovation, and from supplying individual components to becoming an indispensable part of the global computing infrastructure.

Source: nfnews, 21jingji, sina finance, the paper, gdhte

Chinese Medical Device Breaks Through a Long-Standing Barrier in Heart Failure Treatment

0

On August 30, 2026, in Munich, a clinical trial from China took center stage at one of the most closely watched sessions in global cardiovascular medicine.

At the European Society of Cardiology (ESC) Congress 2026, Professor Shaoliang Chen presented the results of the PADN-HF-PH trial during the Hot Line session. Published simultaneously in the New England Journal of Medicine(NEJM), the randomized trial evaluated pulmonary artery denervation, or PADN, in patients with heart failure and pulmonary hypertension caused by left heart disease.

For patients with this condition, the significance of the study goes beyond another positive clinical trial. For more than a decade, physicians have faced a difficult therapeutic gap: as heart failure progresses, pressure can build up in the pulmonary circulation, placing increasing strain on the right side of the heart. Yet treatments that effectively address the heart, the pulmonary circulation and the interaction between the two have remained limited.

PADN is an attempt to intervene in that gap.

Developed in China, the minimally invasive procedure uses a catheter to deliver radiofrequency energy to nerves surrounding the pulmonary artery. By modifying excessive sympathetic nerve activity, the treatment is designed to influence pulmonary vascular resistance and the abnormal interaction between the heart and pulmonary circulation.

The underlying concept is relatively simple, but the clinical problem is not.

Heart failure is not a single disease. As the condition progresses, abnormalities in the left side of the heart can raise pressure in the blood vessels of the lungs. Over time, this increased pressure can increase the workload on the right ventricle, creating a cycle in which the heart and pulmonary circulation place increasing stress on one another.

When pulmonary hypertension develops as a consequence of left heart disease, it is commonly referred to as PH-LHD. It is the most common form of pulmonary hypertension, but it has also been one of the more difficult areas to treat specifically.

Modern heart failure therapy has become increasingly effective. Guideline-directed medical therapy, or GDMT, uses combinations of drugs that target several biological pathways involved in heart failure progression. But treating the underlying heart failure does not necessarily eliminate the abnormal pressure and vascular changes that develop in the pulmonary circulation.

At the same time, drugs specifically developed for other forms of pulmonary hypertension have not consistently demonstrated benefit in patients whose pulmonary hypertension is caused by left heart disease. As a result, physicians have historically had few established options for directly targeting the pulmonary vascular component of the disease.

This is the clinical space into which PADN has entered.

The procedure is based on the idea that the pulmonary arteries are not simply passive blood vessels. They are also influenced by the autonomic nervous system. Excessive sympathetic activation may contribute to pulmonary vasoconstriction, vascular remodeling and the progression of cardiopulmonary dysfunction.

PADN seeks to modify that neural pathway through a catheter-based procedure rather than through another systemic drug. The approach has been developed over more than a decade. Early studies focused on whether the procedure could be performed safely and whether it could improve hemodynamic parameters such as pulmonary vascular resistance and pulmonary artery pressure. Later studies examined exercise capacity and longer-term clinical outcomes.

The PADN-HF-PH trial represents a further step in that evolution because it asks a more consequential question: when PADN is added to contemporary heart failure treatment, does it actually reduce clinical deterioration?

The answer from the randomized trial was encouraging. Conducted across 25 centers in China, the study randomized 264 patients to receive either PADN plus GDMT or GDMT alone. The patients had symptomatic heart failure and pulmonary hypertension associated with left heart disease and were already receiving stable background medical therapy.

The primary endpoint was deliberately designed around events that matter to patients rather than relying solely on changes in laboratory or hemodynamic measurements. It included death, heart or lung transplantation, hospitalization for worsening heart failure, outpatient deterioration requiring intravenous treatment, and clinically meaningful deterioration in six-minute walking distance.

After a median follow-up of 338 days, the Kaplan-Meier estimated two-year incidence of clinical deterioration was 25.7% in the PADN-plus-GDMT group, compared with 51.5% in the GDMT-alone group. The hazard ratio was 0.49, with a 95% confidence interval of 0.30 to 0.82 and a P value of 0.006.

In practical terms, the trial found that patients receiving PADN in addition to medical therapy experienced substantially fewer clinical deterioration events during follow-up. The significance of the result lies partly in what the researchers chose to measure.

A reduction in pulmonary artery pressure or pulmonary vascular resistance can demonstrate that a procedure is changing the physiology of the disease. But for patients and physicians, the more important questions are whether patients remain functional, avoid repeated hospitalization and experience fewer serious clinical events.

PADN-HF-PH therefore moves the evidence beyond physiology alone and toward patient-centered outcomes. The trial also reported improvements in functional and biological measures. Six-minute walking distance, a commonly used measure of exercise capacity in patients with cardiopulmonary disease, improved relative to the control group. The study also found favorable changes in Kansas City Cardiomyopathy Questionnaire scores and NT-proBNP, a biomarker associated with cardiac stress.

The findings do not mean that PADN has solved every question surrounding heart failure-related pulmonary hypertension. A single randomized trial cannot establish how broadly the results will apply to all patients, nor can it determine the full extent of long-term effects on mortality and hospitalization. Longer follow-up and additional studies will be needed.

But the trial does establish something important: a catheter-based intervention targeting pulmonary arterial nerves can be tested against contemporary medical therapy in a randomized setting and can produce a statistically significant reduction in a clinically meaningful composite endpoint.

That distinction matters. For much of modern cardiovascular medicine, major advances in heart failure treatment have come from pharmacology. New drugs have transformed the prognosis of many patients by targeting neurohormonal activation, renal mechanisms and other biological pathways.

The next stage of innovation may increasingly involve combining those therapies with devices and minimally invasive procedures that address different parts of the disease process. PADN represents one example of that broader shift. It also illustrates a changing role for Chinese medical-device innovation.

For decades, China’s medical-device industry was often associated with manufacturing scale, cost advantages and the localization of technologies originally developed elsewhere. Those capabilities remain important. But a different category of innovation is now emerging: Chinese companies are increasingly attempting to develop technologies for clinical problems for which there is no established global product or treatment pathway to copy.

This is the defining challenge of a first-in-class technology. When a product improves on an established device, the development pathway is relatively clear. There are existing benchmarks for safety, performance, clinical endpoints and regulatory approval. A company can study the market and improve upon an established design. A first-in-class therapy has no such template.

The company must establish the mechanism, develop the technology, demonstrate safety, design clinical trials, persuade physicians to participate, build the regulatory case and ultimately convince the medical community that the new treatment deserves a place alongside established therapies. PADN has followed precisely this longer path.

The technology has been investigated for more than a decade, beginning with early feasibility studies and progressing through randomized trials and longer-term follow-up. Earlier research provided evidence that PADN could influence pulmonary hemodynamics and exercise capacity. Subsequent studies sought to determine whether these physiological improvements could translate into meaningful clinical benefit.

The development program then moved beyond China. International studies have been used to test whether the procedure can be reproduced across different healthcare systems, patient populations and clinical teams. The company is also pursuing regulatory and clinical development programs in the United States and other international markets.

This progression is critical because medical-device globalization is fundamentally different from exporting an ordinary consumer product. A device can be physically shipped to another country relatively quickly. A new medical treatment cannot.

Before physicians in another healthcare system adopt it, the technology has to survive multiple layers of scrutiny: clinical evidence, regulatory review, procedural training, physician acceptance, reimbursement considerations and, ultimately, real-world use.For a first-in-class device, the clinical evidence becomes the foundation of the entire process.

This is why the publication of PADN-HF-PH in the New England Journal of Medicine and its presentation at the ESC Hot Line session carry significance beyond the visibility of a single company. They place a Chinese-developed medical-device technology within the same global evidence ecosystem in which new cardiovascular treatments are evaluated.

That does not automatically make PADN a standard treatment. Medical guidelines are based on the totality of evidence, and future recommendations will depend on additional randomized studies, longer follow-up, safety data, reproducibility across populations and regulatory assessment.

But the trajectory is notable. A technology that began as an experimental concept in China has progressed through multiple stages of clinical validation and is now being evaluated on a global stage. That progression also changes the meaning of “going global” for Chinese medical-device companies.

For many years, globalization meant selling a Chinese product overseas. Increasingly, the more consequential form of globalization is becoming something else: bringing a Chinese-developed clinical hypothesis into the global medical community and asking international physicians, regulators and researchers to test it against the same standards applied to technologies developed in Europe or the United States.

PADN provides a particularly clear example because the underlying problem is global.

Heart failure is a major burden across healthcare systems, and pulmonary hypertension associated with left heart disease affects large and diverse patient populations. The clinical challenge is not specific to China. If a new intervention ultimately proves safe, reproducible and effective across different healthcare environments, its potential impact will likewise extend well beyond its country of origin.

The commercial implications follow from the clinical question, rather than preceding it.

If a new therapy becomes accepted as part of the treatment pathway, the market is not necessarily limited to patients who previously received an existing competing device. In areas where there is no established device-based treatment, successful clinical innovation can create a new treatment category.

That is one reason first-in-class technologies attract strategic interest despite their higher development risk. In April 2026, Pulnovo Medical, the company developing PADN, announced a $100 million Series D financing round led by Medtronic, with continued participation from existing investors including EQT, Qiming Venture Partners, GaoRong Capital, OrbiMed and Lilly Asia Ventures. The company said the financing would support clinical development, regulatory activities and international commercialization.

The involvement of a global medical-device company is significant from an industry perspective, but it should not be confused with clinical validation. Investment and commercial partnerships can provide resources, expertise and distribution capabilities; ultimately, however, the medical value of a technology still depends on evidence generated through clinical research. For PADN, the next phase will therefore be at least as important as the milestone achieved in Munich.

The questions are becoming more demanding: Which patients benefit most? How durable are the effects? Can the results be reproduced in other countries? What is the long-term safety profile? How should patients be selected? How should the procedure be integrated with existing heart failure care? And can further studies establish whether the reduction in clinical deterioration translates into longer-term reductions in hospitalization or mortality?

Those questions will determine whether PADN moves from an emerging intervention to a widely adopted treatment.

The broader significance, however, is already visible. For decades, much of the global medical-technology landscape was defined elsewhere. Chinese companies entered markets where diseases had already been classified, treatment pathways had already been established and product categories had already been created. 

Source innovation changes that relationship. When a company develops a technology for a clinical problem that remains unresolved internationally, the goal is no longer simply to compete within an existing market. It is to test whether a new treatment pathway can become part of global medicine. That is what makes PADN worth watching.

Its importance does not rest on the claim that one trial has already transformed heart failure treatment. Rather, it lies in the evidence that a Chinese-developed medical device has progressed from an original scientific concept to randomized clinical testing, high-level international publication and global regulatory development.

The journey is far from over. More evidence will be required before the full place of PADN in clinical practice can be determined. But the direction of travel is unmistakable.

For patients with heart failure and pulmonary hypertension caused by left heart disease, a therapeutic area that has long lacked a clear device-based option, PADN offers a new avenue for investigation.

For China’s medical-device industry, the story is even broader. It demonstrates what becomes possible when innovation begins not with the question of how to improve an existing product, but with a much harder question: what important clinical problem remains unsolved, and can a new technology provide an answer?

The significance of PADN will ultimately be determined by evidence accumulated over the years ahead. Yet the achievement already represents a meaningful shift in the role Chinese medical technology can play in global healthcare.

China is no longer only a market in which new medical technologies are adopted, nor simply a manufacturing base from which established products are exported. Increasingly, Chinese researchers and medical-device companies are attempting to develop the technologies, generate the evidence and propose the treatment pathways that the rest of the world may one day use. PADN is one of the clearest examples yet of that transition.

Source: 36kr, vbdata, bydrug, 2500sz, stcn

Baidu’s Ten-Year Bet on Full-Stack AI

0

To understand China’s leading AI company Baidu today, it is worth asking a simple question: Why would an internet company spend a decade building something so expensive, so technically demanding, and so slow to pay off?

The answer is artificial intelligence. On September 1, Baidu completed the conversion of its Hong Kong listing from secondary to primary status, making it a dual-primary-listed company alongside its Nasdaq listing. 

The move does not itself change the company’s business, nor does it raise new capital. But its timing is significant. AI-related businesses have now accounted for more than half of Baidu’s general business revenue for two consecutive quarters.

AI is no longer simply Baidu’s bet on the future. It is becoming the company’s operating reality. The more important question, however, is what Baidu has spent the past decade building.

Around 2016, the mobile internet was still at the height of its expansion. Traffic, users and monetization dominated the strategy of Chinese internet companies. Li Yanhong, Baidu’s founder and CEO, chose a different path. He began redirecting the company’s resources toward AI and, rather than starting with consumer applications, chose to build from the bottom of the technology stack upward.

Chips. Cloud infrastructure. Foundation models. Applications. It was a particularly demanding route. Chip development requires years of R&D and close coordination across a complex supply chain. Cloud infrastructure requires enormous capital investment. Large models require sustained spending on computing power, algorithms and data. Applications ultimately have to prove their value in the real world.

Failure at any one layer can turn the idea of “full-stack AI” into little more than a corporate slogan. That is why Baidu’s AI strategy is better understood not as a bet on any single model or product, but as an attempt to build an integrated technological system.

The value of full-stack AI does not come simply from owning multiple businesses. It comes from making those businesses reinforce one another. Computing chips determine efficiency. Cloud infrastructure provides the foundation for training and inference. Models turn computing power into intelligence. Applications turn intelligence into user demand and revenue. The requirements generated by applications, in turn, feed back into the development of models, infrastructure and chips. If that cycle works, technology investment stops being merely a cost. It becomes a compounding capability.

Li has described Baidu’s architecture in terms of “chips, cloud, models and agents.” The idea is fundamentally different from the growth flywheel of the mobile internet. In the previous era, scale often came from acquiring users, generating traffic and improving monetization. In AI, the flywheel is more engineering-driven: better computing efficiency lowers training costs; better models expand the range of applications; larger applications generate more real-world demand; and that demand drives further optimization.

This may be the most important, and least visible, part of Baidu’s transformation.

For years, the market was accustomed to viewing Baidu through the lens of search, advertising and the traditional Chinese internet. Under that framework, AI research and infrastructure spending could easily appear as costs weighing on earnings.

But if Baidu is building the infrastructure of an AI company, the same spending has a different meaning. Over the past several years, that transformation has begun moving from laboratories into commercial markets.

Kunlunxin, Baidu’s AI chip business, has continued to advance its commercialization. Baidu Intelligent Cloud has benefited from rapidly increasing demand for AI computing infrastructure. The company’s Ernie family of foundation models has gone through multiple generations of development. AI productivity products and intelligent agents are beginning to attract significant user activity. Apollo Go, Baidu’s autonomous-driving business, has pushed its technology into real-world roads and commercial operations.

These businesses are at different stages of maturity and face very different competitive challenges. But together they form the practical foundation of Baidu’s full-stack strategy.

More importantly, the layers are beginning to interact.

Large-model training creates new demands for computing infrastructure. Computing infrastructure affects the cost and speed of model development. Better models expand the range of AI applications. Real-world applications generate new requirements and data that can feed back into model development.

The potential moat is therefore not simply that one layer is better than its competitors. It is whether the entire system can improve faster because the layers are connected. This is also why AI may demand more patience than the mobile internet ever did.

A consumer application can be tested, adjusted or abandoned within months. Chips, data centers and foundation models operate on entirely different timelines. They require years of accumulated engineering expertise and can absorb enormous resources before producing visible returns.

The difficult part is not recognizing that AI matters. The difficult part is continuing to invest when the payoff remains uncertain. Li has articulated a simple principle for deciding which technologies Baidu should pursue: if success depends heavily on technological advancement and requires long-term iteration, the company should be willing to invest. If technology is not the decisive factor and the attraction is primarily the size of the market, entering the business may not be worthwhile.

That philosophy helps explain why Baidu chose such a difficult path.Of course, technological depth does not automatically translate into commercial success. Full-stack capabilities are not inherently a moat. Chips must compete on performance, cost and ecosystem compatibility. Foundation models face intense competition. Cloud businesses must demonstrate sustainable economics. AI applications must prove that users will return and pay. Autonomous driving must confront safety, regulation and the difficult economics of operating in the physical world.

Ultimately, the market will judge Baidu on those outcomes. But the past decade has established something important: Baidu was not simply chasing an AI trend. It was attempting to build an integrated AI technology stack. That distinction matters as investors reassess the company.

The conversion of its Hong Kong listing into primary status may broaden its investor base. Potential inclusion in the Stock Connect system could bring additional liquidity. A sum-of-the-parts valuation could also allow investors to assess its cloud, chip, autonomous-driving and AI businesses through different industry lenses.

But none of those developments creates value by itself.

The central question is whether the technological system Baidu spent a decade building can generate sustainable growth over the next decade. The first ten years were largely about construction: putting the chips, cloud, models and applications in place and making them work together.

The next ten years will be about proving the economic value of that integration. That is the real meaning of full-stack AI. It is not a list of businesses or a collection of technology buzzwords. It is a willingness to spend years building the hardest capabilities first, and to wait for technology, products and economics to converge.

A decade ago, Baidu made its most consequential decision by betting on AI. Today, the harder test begins: turning that technological foundation into durable growth. Time has already shown that patience can be a competitive advantage. The next chapter will require something more difficult, not merely patience, but returns.

Source; baidu cloud, leidacj, 36kr, gdec