China is a global trading and shipping powerhouse, yet its financial sector still accounts for a relatively limited share of high-value-added business worldwide. For years, large volumes of insurance, reinsurance, shipping finance, offshore trust and other international financial services have been dominated by Western institutions.
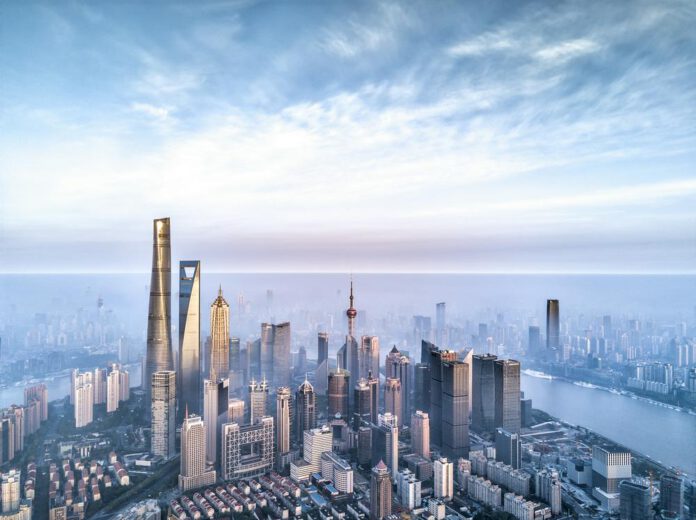
That landscape may now be entering a new phase. With the launch of the Action Plan for the Development of Offshore Finance in Shanghai International Financial Center, Shanghai is accelerating efforts to build an internationally competitive offshore financial system.
Lian Ping, Chairman of the China Chief Economist Forum and President of the International Finance Institute, shares his views on the development of offshore finance in China, the strategic significance of Shanghai’s new offshore financial framework, and the opportunities and challenges it presents for China’s financial sector.
What is the strategic significance of offshore finance for China’s ambition to become a financial powerhouse and for Shanghai’s international financial center?
China is already deeply integrated into the global economy. As Chinese companies and financial institutions expand overseas, offshore finance can provide them with more efficient financial services, risk management and liquidity support. It can also serve foreign companies and economies that trade and invest with China.
More importantly, offshore finance offers China a relatively controllable channel for expanding financial openness. China has not yet reached the stage of completely liberalizing capital flows and currency convertibility. Offshore finance can therefore provide a higher degree of internationalization within a manageable regulatory framework. In that sense, it can become an important source of new momentum for Shanghai as an international financial center.
There is another particularly important dimension. Global offshore markets handle large volumes of high-value-added business, including trade finance, shipping finance, insurance and reinsurance. China has enormous trade and shipping volumes, yet Chinese financial institutions still capture only a limited share of the core financial services generated by these activities.
Developing offshore finance would give Chinese institutions a pathway into these global markets, strengthen their international competitiveness and allow China to capture more of the financial value generated by its own global economic activity.
How will Shanghai build its offshore financial system, and what are the key priorities and stages of implementation?
The framework can be summarized in three concepts: physical concentration, restricted participation and account segregation.
“Physical concentration” means initially concentrating offshore financial activities in Pudong. “Restricted participation” means that transactions will primarily involve non-residents. “Account segregation” requires offshore accounts to remain strictly separate from onshore accounts, ensuring that offshore funds and transactions are clearly distinguished. This is fundamental to risk management.
The Action Plan identifies six priority areas: offshore trade finance, free-trade offshore bonds, offshore reinsurance, treasury-center fund operations, offshore renminbi foreign-exchange trading, and financial services for non-resident individuals.
Implementation will proceed in three stages. By 2027, Shanghai aims to establish the basic rules, risk-management mechanisms and business environment for offshore finance. By 2030, it aims to develop a relatively mature institutional and legal framework. By 2035, the objective is to establish a strategic hub capable of coordinating onshore and offshore finance at a high level.
Offshore renminbi foreign-exchange trading has expanded rapidly since the pilot program began; what does that tell us about the market?
Rapid growth is common when a new market opens, and in this case it also indicates that there was substantial underlying demand that previously lacked an appropriate channel.
The renminbi has become increasingly internationalized, while Chinese commercial banks possess enormous renminbi and foreign-exchange positions. The participation of six major banks in the Shanghai Free Trade Zone therefore naturally generated a rapid increase in trading activity.
The more important indicators going forward will be market liquidity, the range of currencies traded, pricing capacity and the international composition of market participants. The pilot phase is currently dominated by Chinese banks. If more foreign financial institutions are allowed to participate, Shanghai could gradually develop into a genuinely global offshore foreign-exchange market.
What kind of tax framework does Shanghai need to make its offshore financial system internationally competitive?
Taxation is an important component of the competitiveness of any international financial center. Mature offshore centers generally do not simply apply their domestic tax regimes to offshore business. Instead, they develop arrangements tailored to international competition and specific business needs.
Shanghai should therefore avoid managing offshore finance entirely through an onshore tax framework. Offshore markets serve non-resident transactions and operate in an intensely competitive international environment. If the tax burden is significantly higher than that of comparable financial centers, business will naturally move elsewhere.
The appropriate approach is to consider international competitiveness and adopt differentiated policies. Certain strategically important businesses could receive appropriate tax incentives or exemptions, while regulatory mechanisms should simultaneously prevent tax arbitrage, foreign-exchange arbitrage and money laundering.
Across major Asian offshore centers, overall tax levels are broadly in the 12–16% range, although Shanghai should not simply copy any particular jurisdiction. The tax framework should reflect the nature of different businesses and the stage of market development.
Will Shanghai’s development of offshore finance compete with Hong Kong, or can the two centers complement each other?
Competition will inevitably exist, but the more important relationship is one of complementarity and market expansion. China is a very large economy, and as its trade, investment and overseas business continue to grow, the overall demand for offshore financial services will also expand.
Hong Kong is closely connected to the Greater Bay Area and the broader southern Chinese economy, while Shanghai is supported by the Yangtze River Delta, where advanced manufacturing, technology investment and emerging industries are developing rapidly. These different economic hinterlands generate distinct sources of financial demand.
Shanghai and Hong Kong can therefore develop differentiated strengths while competing constructively in global offshore markets. The objective should not simply be to redistribute an existing pool of business, but to expand China’s overall participation in international financial services.
What are the principal financial-sanctions risks China needs to prepare for?
The two most powerful financial-sanctions tools are restricting access to the SWIFT messaging system and freezing overseas assets. These measures have had significant effects on countries such as Iran and Russia.
For China, however, comprehensive financial sanctions would involve much greater costs and international spillovers. China is one of the world’s largest trading economies and an important participant in global finance. Any attempt to exclude China from SWIFT would disrupt a very large volume of international transactions, while alternative infrastructure such as the Cross-Border Interbank Payment System, or CIPS, would become increasingly important.
The more realistic concern is therefore targeted financial restrictions rather than comprehensive sanctions.
Asset freezes also raise fundamental questions about confidence in the international financial system. If assets can be arbitrarily frozen because of political disputes, confidence in the jurisdiction holding those assets is inevitably weakened. China therefore needs to strengthen cross-border payment infrastructure, diversify international asset allocation and enhance the resilience and autonomy of its financial system.
Does the recent increase in global central-bank gold purchases signal a long-term decline in confidence in the dollar, and where might the international monetary system be heading?
The rise in gold prices reflects inflation and geopolitical risks, but the deeper issue is uncertainty surrounding the international monetary system. Persistent U.S. fiscal deficits and rising debt, together with geopolitical tensions, have encouraged some countries to reassess their exposure to dollar assets.
That does not mean the dollar will quickly lose its dominant position. The United States still possesses deep financial markets, extensive international networks and significant institutional advantages. The dollar is unlikely to be displaced by another single currency in the short term.
Over a much longer horizon, however, the international monetary system could become more diversified. Several forms of monetary assets may coexist: sovereign currencies such as the dollar and renminbi; regional or group currencies such as the euro; international reserve assets such as the IMF’s Special Drawing Rights; and gold.
Gold is no longer a conventional currency, but it retains its function as a store of value and a hedge against systemic risk. Its renewed importance reflects broader uncertainty in the international monetary order.
From a 30-, 50- or even longer-term perspective, the global monetary system is undergoing structural change. The renminbi is likely to play a larger international role, but whether it can become one of the world’s principal reserve and international currencies will ultimately depend on a much broader set of factors, including the scale of China’s economy, the depth of its financial markets, technological capabilities and overall national strength.
Source: mindstream, guancha, cls, xinhua